


"Migrant mother of family from Arkansas in roadside camp of cherry pickers, Berrien County, Michigan"
Ilargi: As Europe falls further apart, Ashvin continues his look at the future value of what so many perceive to be the ultimate safe haven: gold. Is it, though? What does it derive its value from, and how does that really work?
Ashvin Pandurangi:

"Fort Knox Gold Mine" - Photo by Kevin Fitzgerrel
Part I of this series, The Future of Physical Gold - Dialectic Foundations, discussed how the concept of money had been fundamentally transformed by the material (rather than ideological) forces of the financial capitalist system. It was no longer just a convenient medium of exchange, unit of account, and store of value, but also became a social and political means of systemic oppression. The leverage embodied in financial instruments (by far the largest component of money in the global economy) imprisoned the very definitions of economic, social and political activity within a strict mode of operation.
The culture imperative of the developed world was financed consumption and apathy, while its political imperative was the concentration of wealth and the appeasement of those being continuously plundered. All of those lacking control of productive assets, including both "debtors" and "savers", found it impossible to maintain their wealth, purchasing power and/or service their debts over time. These people were all "workers" who sold their productive capacity in the marketplace, and received increasingly less value for it over time.
Superficial concessions were frequently granted by the controlling class (i.e. minimum wages, union benefits, bankruptcy process, welfare, wage-arbitraged prices, etc.) and their propaganda was planted deeply in the minds of middle-class dreamers, but that has not stopped the middle-class from relentlessly fading to black. It then becomes clear that any other global monetary system, including "Freegold" (a synthesis of physical gold-based money and debt-based currencies; briefly described in Part I), would serve as a lie for the masses.
It would be another means of convincing people that they actually have not been plundered (it's all in your imagination), and that they can continue their time-honored tradition of financed consumption, albeit with some "fail-safe" mechanisms built into the system that would prevent excessive financial speculation and protect those who wish to save (Glass-Steagall, anyone?). Take a look at this quote from Jean-Claude Juncker and its accompanying commentary (excerpted from the article Trojan Lies on The Automatic Earth):
"When it becomes serious, you have to lie", Juncker, who as the chairman of the regular meetings of eurozone finance ministers is one of the currency union's key spokesmen, said in recent remarks.
Even confirming the existence of discussions on explosive financial issues can quickly turn them into self-fulfilling prophecies and have serious consequences for a country's economy by driving up borrowing costs. "If you are pre-indicating possible decisions, you are fueling speculation on the financial markets, throwing into misery mainly ordinary people whom we are trying to safeguard from this," Juncker said. [1].
Basically, Juncker is telling us that broad-based lies are necessary in modern society to whitewash the underlying reality, because, without them, the underlying reality would become much worse, much more quickly. However, anyone who has attempted to orchestrate a complicated series of lies knows that it is not sustainable and will only make the underlying situation psychologically more difficult to bear, once the lies become plainly contradictory and/or ridiculous.
Indeed, lies must be continuously advertised and sold like any other product, and the propaganda industry is struggling to turn a profit these days. The reason is because human ideas cannot fundamentally change the underlying material reality of the human condition, and now, despite our propensity to tell ourselves lies, the reality has become much too plain and stark to consciously ignore. Instead, the deteriorating material reality will drive our ideas and our willingness to accept the ideas of others, just as the Marxian dialectic would dictate.
The fundamental problem in the material sphere of financial capitalism is a lack of aggregate (effective) demand in the developed consumer/investment markets of the global economy. Annual aggregate demand in the private economy can be simply represented as (nominal GDP + change in private credit). GDP obviously incorporates private consumption, investment and non-transfer public expenditures (i.e. social security, welfare benefits, etc. are not counted), while also adding trade surpluses and subtracting trade deficits. [2].
In the capitalist system, then, public credit (deficit) growth and personal savings (non-investment) would act as the "demand of last resort". The latter typically sits very still in a recession until it is finally forced to come out for the purchase of necessities and/or to avoid an outright collapse in purchasing power. To understand why private consumption, investment, savings and private/public credit growth have all begun to stagnate or substantially decline in the developed world, and why they will soon follow suit in "emerging markets", we must start with a basic history of "wealth" creation in a capitalist system.
First, we should discuss the meaning and sources of "value" in this system as a foundation for why the private demand for commodities and financial investments (the availability of excess wealth) is constrained over time. Karl Marx realized that a commodity's value had evolved from what it once was in the relatively simple barter societies of our past, as its "exchange-value" became distinct from its "use-value" and allowed for the production of "surplus value". The following excerpt is taken from Debunking Economics, a book written by the notable Australian economist, Dr. Steve Keen [emphasis mine]:
Marx: "The exchange of commodities, therefore, first begins on the boundaries of such communities, at their points of contact with other similar communities, or with members of the latter... The constant repetition of exchange makes it a normal social act. In the course of time, therefore, some portion at least of the products of labour must be produced with a special view to exchange. From that moment the distinction becomes firmly established between the utility of an object for the purposes of consumption, and its utility for the purposes of exchange. Its use-value becomes distinguished from its exchange-value." [Debunking Economics, Chapter 13]

From Living in the Spiral
Marx basically gives us a brief description of the transition from a simple barter economy to a production-based economy. In the initial stages of barter at the "boundaries" of communities, a commodity's ratio of exchange with another commodity is a "matter of chance" and may be influenced by their perceived utility in consumption. As the benefits from barter accrue over time, however, a repetitive pattern of trading develops and leads to the production of certain commodities with the sole purpose of using them in trade, rather than consuming them.
It is at this time when the commodity's exchange-value is separated out from its use-value, with the former being the sole determinant of its value in trade. Both use-value and exchange-value can be thought of as objectively determined values, since the former is the utility of a commodity performing a specific function, and the latter is the sum of the use-values consumed in its production. Dr. Keen clarifies the commodity dialectic with the use of labor as an example, in his research paper entitled, A Marx for Post Keynesians:
Keen: "To apply his Commodity Axioms to labor-power and the origin of surplus value, Marx had first to identify labor-power's exchange-value and use-value. He argued that the exchange-value of labor-power was its value, the means of subsistence, which could be represented by a bundle of commodities, while its use-value was labor, the ability to perform work. The former identification was hardly novel; however, the latter was revolutionary, in two senses. [A Marx for Post Keynesians, pg. 8]."
Stopping here for a moment, it is important to understand why increased systemic complexity fundamentally changes and constrains the role of commodities, including those claiming to be "wealth reserves", in the political economy. Dr. Keen talks about the implications of systemic complexity a bit in terms of "representative agent" models in mainstream macroeconomics [emphasis mine]:
Keen: "I have more to say about this in Chapter 12, but here it is worth noting that representative agent macroeconomics amounts to assuming that the economy consists of a single individual producing and consuming a single commodity. However complex might be the reasoning used by such aficionados as Paul Krugman, the realm of applicability of this theory is thus that of Robinson Crusoe, living off coconuts before the arrival of Man Friday. It beggars belief that anyone who truly knew where this notion had come from would attempt to apply it to something as complex as a modern, multi-commodity, multi-million person economy." [Debunking Economics, Ch. 9]
FOFOA, the most popular Freegold advocate still blogging, uses two "representative agents" from a model "game" to illustrate why physical gold will be"tapped" by natural market forces to serve the role of global wealth reserve over any other monetary asset, since it is a natural "focal point" for investors to place their excess currency wealth in upcoming years. Although this example may not necessarily entail the same flawed assumption used by Neo-classical economists to model aggregate market behavior, it follows a very similar logic [my emphasis]:
FOFOA: "Consider a simple example: two people unable to communicate with each other are each shown a panel of four squares and asked to select one; if and only if they both select the same one, they will each receive a prize. Three of the squares are blue and one is red. Assuming they each know nothing about the other player, but that they each do want to win the prize, then they will, reasonably, both choose the red square [..]
[..] is why money not only can be split into separate units for separate roles, one as the store of value and the other to be used as a medium of exchange and unit of account, but why it absolutely must and WILL split". [Focal Point: Gold].
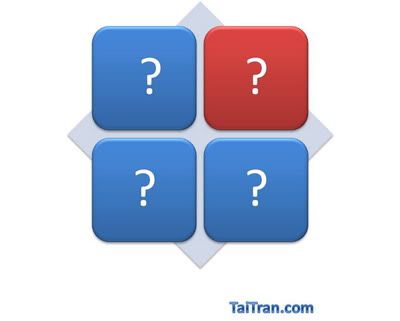
It should be clear that a simple "game" with simple "rules", such as the square game above, cannot provide insights into the monetary decisions of actors operating within complex financial markets, where irrational and non-linear behavior is THE dominant and "emergent property". Getting back to Marx's commodity dialectic, we can proceed to explore the two "revolutionary" insights he had with regards to use-value (in the context of labor):
Keen: "Firstly, in contrast to Smith or Ricardo, Marx gave use-value an active role in political economy. Secondly, he asserted that, under specific circumstances, use-value could be quantitative--though what was being quantified was not abstract satisfaction, as in neoclassical analysis, but the objective function of the commodity in question." [..]
"...Thus, in the case of this commodity [labor], use-value and exchange-value could both be measured in the terms of the exchange-value of commodities. He then applied axiom 4 above--that the use-value of a given commodity plays no role in determining its exchange-value--to conclude that these two value magnitudes would be different, and that this difference was the source of surplus value." [A Marx for Post Keynesians, pg. 8]
So the worker's ability to labor ("labor-power") is sold in the labor market for its exchange-value (= "subsistence wage"), but it is bought by the employer for its much higher use-value (= sum of the exchange-values of the commodities it produced). For example, the employer might pay a worker $6/hour for his ability to produce widgets over 10 hours, would only need 5 hours of widget production to justify the $60 subsistence wage and would therefore generate surplus value from the widgets produced during the extra 5 hours. Labor-power, therefore, is a unique commodity because its use-value can be measured in terms of exchange-values in certain circumstances.
What Marx eventually failed to incorporate into his theory of value was only the fact that all commodity inputs to production possessed a similar inequality of use and exchange-values. There is only one major modification needed for this general rule, and that is for financed-assets which provide returns (bonds, shares, currency deposits, land, etc.). These assets derive value directly from their use-value, which happens to be the expectation of their future exchange-value. This crucial distinction sets the stage for Minsky's "Financial Instability Hypothesis", discussed in Part III, and it is fully consistent with Marx's commodity dialectic approach to value.
Before moving on, it should be pointed out that physical gold as a monetary asset in the Freegold system does not fall under the category of being a "non-commodity", or a good that is not mass-produced for exchange and/or use in the production process (i.e. rare statutes, antiques, etc.). Dr. Keen proposes that a final axiom is needed to encompass these "non-commodity" goods, as well those that temporarily exist in the netherworld of being neither a commodity nor a non-commodity (i.e. brand new technological goods):
Keen: "Products which are not part of the system of reproduction of products are not truly commodities, and hence not fully bound by the dialectic of commodities. [Axiom] [..]
This suggests that the products of technological development--which will in time become commodities as they are integrated into the system of reproduction--are liable to have their initial prices set by forces in addition to their costs of production. Perceived utility is one such additional force[..]
[..] ...the price of a newly developed product is likely to be above its exchange-value, but to be driven towards this over time by the forces of competition and commodification." [A Marx for Post Keynesians, pg. 14-15]
Since Freegold envisions physical gold as being the global reserve asset, and certainly not any sort of technological good, it is fair to say that gold will be "commodity" within the industrial capitalist system of exchange subject to Marx's dialectic. Indeed, as argued in Part I, gold would find it impossibly difficult to trade completely independent of this broader system, and most likely the financial system as well. Therefore, we can return to evaluating the process of wealth creation and preservation under the Freegold system when gold is subject to the commodity dialectic.
Freegold's flawed conception of value stems from Austrian economics, as clearly reflected in FOFOA's piece, The Value of Gold. Although he correctly states that Karl Marx's "Labor Theory of Value" is flawed, he goes on to accept the even more flawed "Marginal Utility Theory of Value" (MTV) advocated by the "Neo-Classical" and "Austrian" schools of thought. The perspective informing the latter is captured well in Principle of Economics, written by the founder of Austrian economic theory, Carl Menger [emphasis mine]:
Whether a diamond was found accidentally or was obtained from a diamond pit with the employment of a thousand days of labor is completely irrelevant for its value. In general, no one in practical life asks for the history of the origin of a good in estimating its value, but considers solely the services that the good will render him and which he would have to forgo if he did not have it at his command...
Following this logic, FOFOA concludes that the marginal utility of purchasing additional physical gold units will not diminish, because its utility in preserving a given level of purchasing power will always remain the same, as long it remains a monetary asset that is independent of the official currency. [3]. However, Menger's subjective and simple conception of utility does not translate to the complex political economy of capitalism, where the value of a monetary asset is determined by either its exchange-value on a market or its objective use in producing future exchange-values.

From A Marx for Post Keynesians by Dr. Steve Keen
This comprehensive view of commodity dialectics casts an even larger dispersion on Menger and Freegold's MTV foundation, which only considers one circuit of our complex political economy, and that too in a subjective manner. In this circuit, the end goal of producing commodities is to sell them into a market for a profit and use all of that profit to consume more commodities (C-M-C), without any creation of surplus value in the process. Therefore, the utility of monetary capital in this circuit, whether mediums of exchange or "pure" wealth reserves, is solely a subjective expression of commodities desired, and absolutely determines its value in the capitalist system [emphasis mine]:
FOFOA: "...let's take a quick look at the marginal utility of gold as a store of value[..]
Now say he buys one more $55,000 gold eagle coin, and then another, and another, and so on until all his cash is gone. In the end he will have 26 gold coins. And here's the question: Will that 26th gold coin purchase provide the same utility or diminished (less) utility than the first? Remember, the only utility of gold coins is that they retain their value for thousands of years. That's all they do. And hoarding them doesn't interfere with any other economic activity, at least not when they are not "official money." [The Value of Gold]
As Marx articulated, however, a more essential circuit must (and does) exist in the capitalist economy, where capitalists use monetary capital to purchase commodity inputs (labor, raw materials) with the end goal of creating and realizing surplus value. The following excerpts clarify the capitalist's "wealth accumulation circuit" (M-C-M+) and are contained within Keen's paper debunking Say's Law, entitled Nudge Nudge, Wink Wink, Say No More, and also Debunking Economics:
Marx: "The expansion of value, which is the objective basis or main-spring of the circulation M-C-M, becomes his [the capitalist's] subjective aim, and it is only in so far as the appropriation of ever more and more wealth in the abstract becomes the sole motive of his operations, that he functions as a capitalist... Use-values must therefore never be looked upon as the real aim of the capitalist. Neither must the profit on any single transaction. The restless never-ending process of profit making alone is what he aims at." Nudge Nudge, Wink Wink, Say No More, pg. 4)
Keen: "Since Say’s Law and Walras’ Law are in fact founded upon the hypothesised state of mind of each market participant at one instant in time, and since at any instant in time we can presume that a capitalist will desire to accumulate, then the very starting point of Say’s/Walras’ Law is invalid. In a capitalist economy, the sum of the intended excess demands at any one point in time will be negative, not zero. Marx’s circuit thus more accurately states the intention of capitalists by its focus on the growth in wealth over time, than does Walras’ Law’s dynamically irrelevant and factually incorrect instantaneous static snapshot." (Debunking Economics>, Ch. 9)
As mentioned before, and contrary to what many official "Marxists" and "Neo-Classical" critics say, Marx did not believe a commodity's use-value had no role to play in the creation of surplus value within the M-C-M+ circuit. The following excerpts from Dr Keen's paper, entitled Use-Vale, Exchange-Value and the Demise of Marx's Labor Theory of Value, further explain Marx's initial analysis of surplus value in the industrial capitalist economy [emphasis mine]:
Marx: "We are, therefore, forced to the conclusion that the change originates in the use-value, as such, of the commodity, i.e. its consumption. In order to be able to extract value from the consumption of a commodity, our friend, Moneybags, must be so lucky as to find, within the sphere of circulation, in the market, a commodity, whose use value possesses the peculiar property of being a source of value." (pg. 5)
Keen: "Marx specifically referred to the use-value of a machine being greater than its [exchange] value, and in contrast to his discussion of depreciation in Capital, dissociated the productivity of a machine from its depreciation. The use-value of a machine will differ from its exchange-value and, as with labor, we can assume that its use-value will be "significantly greater than its value." In practice this will mean that the amount it loses in depreciation will be significantly less than the amount it contributes to the value of output, and it will, with labor, be a source of surplus value." (pg. 7)
After that lengthy, yet "valuable" bedrock of wealth creation, we can return to the problem of insufficient aggregate demand in a capitalist system. In Part III, we will discuss how the creation of surplus value via production in the M-C-M+ (wealth accumulation/concentration) circuit implicates an inherent problem for the system, since wealth is only realized from this value when it is monetized in a market. Over-supply of commodities in the production process on a consistent basis leads to negative excess demand in the entire economic system, as a sum of the C-M-C and M-C-M+ circuits (a clear violation of Say's "Law").
Some of the "real-world" economic results of this process will also be discussed, and then the financial dynamics of capitalism, as articulated by Hyman Minsky and Dr. Keen, can be explored to explain why a process of hyperinflation, if and when it finally occurs, will still not "cure" the "realization problem". Finally, we can begin to talk concretely about how all of these trends will impact the future of physical gold in the political economies of human civilization. Far from being an irrelevant monetary asset, physical gold will have a very important role in certain parts of the world and at certain scales of economic activity.
However, the "investment opportunities" implicated by the theory of Freegold will be revealed as exaggerated and misleading. Until then, I ask that readers carefully consider the Marxian approach to dialectic evolution and economic value in a capitalist system. An accurate understanding of Marx, unique to even many of his "followers", provides an invaluable perspective from which to view the global economy's fundamental nature and path at this unique point in history. The material implications of this perspective are quite bleak, but, nevertheless, we will soon begin to trust in those striking, yet simple portraits that have been etched deeply into our honest minds.
Our account of this science will be adequate if it achieves such clarity as the subject-matter allows; for the same degree of precision is not to be expected in all discussions, any more than in all products of handicraft.
Aristotle, Nicomachean Ethics
ECB's Balance Sheet Contains Massive Risks
by Matthias Brendel and Christoph Pauly - Spiegel
While Europe is preoccupied with a possible restructuring of Greece's debt, huge risks lurk elsewhere -- in the balance sheet of the European Central Bank. The guardian of the single currency has taken on billions of euros worth of risky securities as collateral for loans to shore up the banks of struggling nations.
On the green fields near Carriglas, halfway between Dublin and Ireland's west coast, the wind whistles eerily around rows of half-finished houses. Most of these buildings are roofless, leaving their bare walls unprotected against the elements. Even the real estate brokers' for-sale signs and the project offices are gone. Hardly anyone in Carriglas believes that the houses will ever be finished. There are many of these ghost towns in Ireland, including 77 in small County Longford alone, which includes Carriglas. They could end up costing German taxpayers a lot of money, as part of the bill to be paid to rescue the euro.
That bill contains many unknowns, but almost none of them is as nebulous as the giant risk lurking in the balance sheet of the European Central Bank (ECB), in Frankfurt. Many bad loans have now ended up on that balance sheet, including ones that were used to build houses like those in Carriglas and elsewhere. No one knows how much they are worth today -- and apparently no one really wants to know.
Since the beginning of the financial crisis, banks in countries like Ireland, Portugal, Spain and Greece have unloaded risks amounting to several hundred billion euros with central banks. The central banks have distributed large sums to their countries' financial institutions to prevent them from collapsing. They have accepted securities as collateral, many of which are -- to put it mildly -- not particularly valuable.
Risks Transferred to ECB
These risks are now on the ECB's books because the central banks of the euro countries are not autonomous but, rather, part of the ECB system. When banks in Ireland go bankrupt and their securities aren't worth enough, the euro countries must collectively account for the loss. Germany's central bank, the Bundesbank, provides 27 percent of the ECB's capital, which means that it would have to pay for more than a quarter of all losses.
For 2010 and the two ensuing years, the Bundesbank has already decided to establish reserves for a total of €4.9 billion ($7 billion) to cover possible risks. The failure of a country like Greece, which would almost inevitably lead to the bankruptcy of a few Greek banks, would increase the bill dramatically, because the ECB is believed to have purchased Greek government bonds for €47 billion. Besides, by the end of April, the ECB had spent about €90 billion on refinancing Greek banks.
Former Bundesbank President Axel Weber criticized the ECB's program of purchasing government bonds issued by ailing euro member states. In the event of a bankruptcy or even a deferred payment, the ECB would be directly affected.
But even greater risks lurk in the accounts of commercial banks. The ECB accepted so-called asset-backed securities (ABS) as collateral. At the beginning of the year, these securities amounted to €480 billion. It was precisely such asset-backed securities that once triggered the real estate crisis in the United States. Now they are weighing on the mood and the balance sheet at the ECB.
No expert can say how the ECB can jettison these securities without dealing a fatal blow to the European banking system. The ECB is in a no-win situation now that it has become an enormous bad bank or, in other words, a dumping ground for bad loans, including ones from Ireland.
Ireland Not Yet Rescued Yet, Despite Bailout
The Emerald Isle experienced an unprecedented boom that ended in 2007, followed by an equally severe crash. Irresponsible real estate sharks, unscrupulous bankers and populist politicians had ruined the country's finances. It was forced to spend €70 billion to support its banks, even as the government itself was all but bankrupt. In November 2010, the Europeans came to the rescue of the Irish with €85 billion from their joint bailout fund. But Ireland is still far from being rescued.
Bank branches line the main street in the small town of Longford. Loans are no longer available here, says an employee with the EBS Building Society, noting that nowadays the bank only accepts savings deposits. A blue information brochure on the table explains what borrowers can do if they encounter financial difficulties. "Please do not ignore the problem," the brochure implores.
But more and more Irish are indeed ignoring the problem and have simply stopped making payments on their loans. Like other banks in Ireland, EBS -- which issued more than a fifth of all Irish mortgages -- had to be rescued by the Irish government. The fact that EBS, a relatively small bank specializing in home loans, was able to issue so many mortgages is the result of a practice that was commonplace before the crisis and ultimately almost led to the collapse of the financial system.
Mortgage loans were bundled into packages worth billions, allowing the associated risks to be transferred to the international capital markets. They disappeared from the banks' books, allowing lenders like EBS to provide funding for even more real estate in the island nation. By 2007, German insurance companies and savings banks, in particular, were buying up Irish residential mortgage-backed securities. However, in 2008, the international investors became increasingly nervous. The asset-backed securities at EBS -- known as Emerald 1, 2 and 3 -- suddenly slid into negative territory.
An Irish Time Bomb
But the Irish seemingly had a solution. "We wanted to preserve our good relations with our old business partners," says one of the loan experts. In the spring of 2008, investors bought back Emerald 1, 2 and 3, and EBS took back the mortgage loans temporarily. The investors could hardly believe their good fortune. Then EBS packaged the loans from the asset-backed securities with other mortgage loans, creating Emerald 5, an Irish time bomb containing about €2 billion in loans.
But, by 2008, international investors were no longer interested in this type of security. Asset-backed securities were already seen as toxic, and the market had collapsed. But EBS knew that the ECB had pledged to accept such securities as collateral for fresh cash. "We didn't have enough bonds to submit to the ECB, so we built Emerald 5," says the EBS employee. Many others did the same.
According to the Association for Financial Markets Europe (AFME), the face value of asset-backed securities newly launched on the European market in 2010 amounted to a tidy sum of €380 billion.
However, the majority of those securities, worth €292 billion, were never offered for sale. Instead, they served one particular purpose: to obtain fresh cash from the central banks.
According to AFME figures, the total value of all outstanding asset-backed securities in the euro zone and the United Kingdom is an almost unimaginable €1.8 trillion. Of course, not all asset-backed securities are toxic. German banks, for example, package together car or small-business loans to ease pressure on their balance sheets.
But the securities that end up at the ECB from peripheral countries like Greece or Ireland are often of questionable value. The central bank is supporting lenders that are in fact no longer viable. And the bombs continue to tick.
Three years after it was launched, things are looking grim for Emerald 5. Eight percent of borrowers are more than three months behind on their loan payments, and of those, a third are more than 12 months behind. The Moody's rating agency has now reduced its rating of Emerald 5 to A1 and announced a further downgrade to A3 unless the security finds new supporters soon. According to current rules, if it slips below a rating of A, it can no longer be submitted to the ECB. And then?
Does The ECB Know How Safe Its Collateral Is?
The ECB maintains a list of "eligible assets," a sort of seal of approval for securities. Every major bank in the euro zone must have such securities, such as bonds or government bonds, or it would be excluded from the money market. There are currently 28,708 securities on the ECB list, with a total value €14 trillion at the end of 2010.
The national central banks determine which securities are placed on the list and under what conditions. "The ECB has no obligation to supervise the central banks, nor does it have the ability to monitor individual central banks," explains an ECB spokesman.
In other words, ECB President Jean-Claude Trichet doesn't even know exactly what kinds of risks he is taking on. In principle, the conditions for ECB investment-grade securities are outlined in a 37-page document, most recently updated in February. To keep the risks for the central banks within reason, some of the haircuts on securities are very high, comprising up to 69.5 percent of the value of a security.
However, the degree to which individual central banks strictly adhere to these rules varies. This leads to irregularities that should simply not occur in a bank, let alone a central bank. For example, Depfa Bank, the Irish subsidiary of the scandal-ridden German bank HRE, had 78 securities placed on the ECB's list of investment-grade securities in February. According to documents SPIEGEL has obtained, 25 of those securities appear not to have been sufficiently discounted.
Pattern of Overstating Collateral Values
An inquiry about these incorrectly valued securities elicited the following nonchalant response from the Central Bank of Ireland: "Thank you for the information. The discount for XS0226100310 should be 46 percent. We will apply this discount in the next few days." This meant that the owners of the security could borrow about 20 percent less money from the ECB.
Only after a second inquiry did the Irish central bankers wake up. On Feb. 28, they almost doubled the discounts on 21 additional Depfa securities. Only three securities, for which the Central Bank of Luxembourg was responsible, initially escaped this fate. As a result, the owners of the Depfa securities were initially spared losses of up to €10 million -- until April 1, when Luxembourg also caught up. "The rating of the Depfa securities was changed in early April, which resulted in an updating of the discount," says the Central Bank of Luxembourg, noting that this is in conformity with the current rules of the euro system.
Ireland's central bank turned a blind eye for weeks to two other debt instruments issued by Irish mortgage lender EBS, with a total face value of €1.3 billion. Even though the instruments had only a B rating, they were valued as first-class securities. "We are not aware of this," says the central bank.
After being repeatedly queried about this discrepancy, EBS finally engaged Fitch Ratings, which promptly provided both securities with its rating of "A-" on April 11. This pattern was repeated several times. The quality of a security was tested, the central bank was contacted, it thanked us for the tip and then adjusted the balance-sheet value of the collateral. Such inadvertent or intentional sloppiness doesn't cast the ECB and its affiliated central banks in a very good light. It also shows that the incentives for rating agencies, which collect large sums of money each time they rate such asset-backed securities, are still questionable.
Although stricter guidelines for the central banks came into effect on March 1, 2011, no one seems to have paid much attention to them. The Central Bank of Luxembourg, for example, still placed 197 asset-backed securities on the ECB list on March 4. After several inquiries were made, the number was reduced to 179 on March 8 and to 146 on March 16.
The quality of securities used as collateral with the Dutch central bank is apparently much higher. On March 8, Fitch rated 281 asset-backed securities held by the central bank, giving its top rating of AAA to 54. These securities were last reviewed before the beginning of the financial crisis and, oddly enough, have not suffered at all since then.
A small team of Fitch employees in London completed the mass rating. The move ensured that securities worth a total of €50 billion were prevented from being removed from the ECB list.\ "We have observed the selection criteria for collateral in the euro system at all times," writes the Dutch central bank. It also notes that the ratings for the asset-backed securities were confirmed by "monitoring reports" prior to March 1.
The handling of these securities is surprising, particularly as they pose an ongoing risk until well into the future, with maturities ranging from 30 to 90 years. Many asset-backed securities are now in constant decline. In the fall of 2008, the Frankfurt-based central bankers already had to concede that the ECB could face losses as a result of its acceptance of asset-backed securities as collateral.
Following the bankruptcies of the German branch of Lehman Brothers, the Dutch bank Indover and three subsidiaries of Icelandic banks, the ECB was stuck with the failed banks' collateral. They had a total face value of €10.3 billion and consisted "primarily" of asset-backed securities, according to an ECB announcement.
No one really knows how high the central bank's risk is in the crisis-ridden countries of Ireland, Portugal, Greece and Spain. But Bundesbank statistics provide an indication of how drastically the situation has changed in Europe. They show that these countries' liabilities to the euro system have risen to €340 billion within about three years. Since the countries are disconnected from the international capital market and domestic savers have only limited confidence in their banks, other European central banks -- most notably the Bundesbank -- are forced to inject more and more money.
Call for a Reform of European Central Banks
Hans-Werner Sinn questions whether this can succeed in the long term. The president of the Munich-based Ifo Institute for Economic Research believes that a reform of the system of European central banks is urgently needed. He wants limits imposed on the autonomy of national central banks when it comes to recognizing securities as collateral. He has also called for "higher country-specific price discounts for securities submitted as collateral." The banks in these countries would slowly have to return to refinancing themselves in the normal capital market.
The ECB stresses that the securities will only have to be realized if the banks actually declare bankruptcy. But as the drama in Ireland shows, the central banks are walking a very fine line. By applying a great deal of pressure, ECB President Trichet made sure that the Europeans came to the Irish government's aid so that Ireland was able to protect its banks from collapse. This spared the central bank the embarrassment of having to realize the precarious instruments among its asset-backed securities, which are based on real estate loans in County Longford and elsewhere.
But if the euro crisis rumbles on, the worst-case scenario isn't all that far away. To ensure its national survival, Ireland should reject the European rescue effort and, instead, accept the failure of its banks as a necessary evil, Morgan Kelly recently said. The renowned professor of economics at University College Dublin knows who would be especially hard-hit by such a step: the ECB. "The ECB can then learn the basic economic truth that if you lend €160 billion to insolvent banks backed by an insolvent state, you are no longer a creditor: you are the owner" Kelly wrote in the Irish Times earlier this month.


Eurozone: Frankfurt’s dilemma
by Ralph Atkins - Financial Times
“Events in Greece have brought the euro area to a crossroads: the future character of European monetary union will be determined by the way in which this situation is handled.”
Jens Weidmann, Bundesbank president and European Central Bank governing council member, Hamburg, May 20.
By rights, the ECB could have abandoned Greece long ago. Nothing in the rule book says it must prop up countries at risk of economic collapse. If anything, the architects of the monetary union, launched in 1999, envisaged the opposite. Because members would share a currency but not spending and tax policies, governments were meant to take responsibility for their own finances – the “no bail-out” principle was enshrined in a European Union treaty. Logically, a nation that flouted the rules as recklessly as Greece should be left to its fate.
Faced in recent weeks, however, with the renewed fears of a Greek default, the ECB has balked. With increasing vehemence, the euro’s monetary guardian has warned of catastrophic effects across the 17-country currency union. Jean-Claude Trichet, ECB president – with less than six months before his eight-year term expires – has refused to discuss any debt restructuring for the nation, storming out of a meeting of eurozone finance ministers in Luxembourg this month when it was raised.
His colleagues, including Mr Weidmann of the Bundesbank, have raised the stakes. They warn that if politicians take even a modest step towards a restructuring, the ECB will cut Greek banks off from its lifesaving liquidity supply, triggering a financial collapse that would push the country’s economy into the abyss. It is the central bank equivalent of nuclear deterrence: defy us and we will blow up the world. How the ECB responds to the conflicting pressures created by the Greek crisis matters enormously.
Shunned by financial markets, the country’s banks survive only because the Frankfurt-based central bank meets in full their demands for liquidity against collateral of rapidly declining quality. Early next month, the ECB has to decide whether to continue that eurozone-wide “unlimited liquidity” policy; so far it has said it will last only until early July. The bank also owns about €45bn of Greek government bonds, acquired during the past year as part of efforts to calm financial market tensions.
Mr Trichet has piled pressure on Athens to reform its uncompetitive and overregulated economy, especially through an accelerated privatisation programme. But if this fails, he or Mario Draghi, the Italian central bank governor expected to succeed him on November 1, will face a dilemma. They will have to decide whether the ECB pulls the plug on Greek banks, leaving governments to decide whether to rescue the country. Otherwise, they will have to jettison the rule book completely and throw money at the problem, perhaps rescuing the euro but at enormous cost to its long-term credibility.
“All of those options are potentially lethal for the eurozone,” says Thomas Mayer, chief economist at Deutsche Bank. Taxpayers elsewhere, particularly in northern Europe, may revolt at demands for fresh help. “But the ECB becoming a backstop for Greece would amount to ‘monetary financing’ [central bank funding of governments], which is forbidden by European Union treaty.”
For the ECB, the turning point was last May. Brutally exposed by the recession that hit Europe after the collapse of Lehman Brothers investment bank in September 2008, Greek fiscal problems exploded into a eurozone-wide crisis. Financial market tensions rose alarmingly as fundamental flaws were exposed in the construction of the monetary union.
The ECB helped persuade eurozone political leaders to assemble a €750bn rescue plan with the International Monetary Fund. It also took action itself. For Greece, it suspended the minimum rating requirement for government-backed collateral used in its liquidity offers, a concession since granted to Ireland. Greek banks could continue to tap the ECB for funds, no matter how far the country was downgraded by rating agencies (it has now reached “junk” status). For the eurozone as a whole, the bank stepped up the provision of unlimited liquidity.
The ECB attracted far more controversy when it decided to start buying eurozone government bonds. The immediate objective of the “securities markets programme” was to try to calm the markets. Officially, it would ensure market interest rates remained in line with the rate deemed necessary to control inflation. But many, especially in Germany, feared it was aiding and abetting fiscally irresponsible governments, violating the spirit of eurozone rules. Axel Weber, then Bundesbank president, publicly opposed the policy. In private, as many as four other ECB governing council members opposed the step.
By declaring it would act as a backstop in bond markets, the ECB bought the eurozone time. A year later, however, the securities markets programme has failed. The debt crisis has spread to Ireland and Portugal, both now subject to ECB-backed international bail-out plans. Greek bond yields have soared this week to record highs as investors shun the country’s debt, with nervousness spreading to countries such as Spain.
Although accounting together for only about 5 per cent of eurozone gross domestic product, Greek, Irish and Portuguese banks today take about €242bn of ECB liquidity – 55 per cent of that provided to the eurozone financial system. The ECB stipulation that it provide liquidity only to solvent banks against adequate collateral has been pushed to the limit.
As such, the risks and conflicts of interest the ECB faces have multiplied. Under the securities markets programme, it acquired €75bn in government bonds, almost two-thirds of which are Greek. It also has on its books perhaps €150bn in other financial assets put up as collateral by Greek banks, much of which is backed by Athens.
. . .
Should Greece default, the value of those holdings would decline sharply. The ECB bought the bonds at market prices, which assumed some risk of default, so the immediate losses might be manageable. JPMorganChase calculates that, with €81bn in capital and reserves, eurozone central banks could withstand even a 50 per cent “haircut”, or discount, on Greek bonds. But if write?downs on Portuguese and Irish bonds followed, eurozone governments might be forced to provide billions of euros to rebuild the ECB’s balance sheet.
According to one view, the ECB has been caught by the consequences of actions it took a year ago. “They are basically trapped. They are now like many people in the banking system in calling out for no debt repudiation because they are so exposed,” says Charles Wyplosz of the Graduate Institute in Geneva.
The ECB’s role was deliberately limited, unlike those of “activist” central banks such as those of the US and UK, Prof Wyplosz argues. “We knew there would be a risk of indiscipline by member states such as Greece. In a monetary union without a fiscal union, you have incentives for governments to piggy-back on the prudence of others and a currency regime that protects you from an immediate financial market backlash.”
Another, more charitable, explanation is that the bank finds itself obliged by the mistakes in the eurozone’s construction to act pragmatically. “The ECB sees that over the past half century, the economic systems of advanced countries have become based on bank leverage and inter-linkages that are predicated on the assumption that governments don’t default,” says Julian Callow of Barclays Capital. “If you did have any kind of debt restructuring, even a ‘soft’ one, that assumption would really be shaken.”
What will happen next? Possibly helping the ECB are brighter economic prospects for the rest of the eurozone, which have boosted the chances of countries such as Greece easing their plight through economic growth. But in another sense, robust growth in countries such as Germany and France has compounded the ECB’s difficulties – it is much harder to set interest rates for the zone as a whole when there is a real chance of a big economic shock – a default – from one of its smallest members.
The immediate priority is to put Athens’ reform programme back on track. The ECB, with the European Commission and IMF, is part of the “troika” negotiating measures to restore Greek public finances to a sustainable basis. As part of those efforts, it is working on Greek banks’ funding plans – thrashing out ways to reduce their dependence on its liquidity. Similar plans are being drawn up in Portugal and Ireland. Once they are ready, the ECB could edge towards the pre-crisis system of auctioning liquidity rather than simply providing banks with as much as they need.
. . .
But to escape the potential dilemma it faces over Greece – as well as Ireland and Portugal – the ECB requires eurozone governments to take over responsibility for resolving the immediate crisis and the longer-term problems facing the monetary union. So far, their willingness has fallen short of hopes in Frankfurt. This year, Mr Trichet lobbied for EU rescue funds set up following last year’s crisis to be given powers to intervene in government bond markets, allowing them to act as backstop instead of the ECB. He was rebuffed.
The bank is disappointed, too, by steps taken to beef up eurozone fiscal rules to prevent Greek-style crises; it wants financial sanctions imposed automatically on the worst offenders. And it has been alarmed by German attempts to make explicit the circumstances in which private investors would be hit in future bail-outs. In its view, Berlin’s crass understanding of financial markets has scared off potential outside investors in countries such as Greece.
If Greece now requires fresh outside financial help, the ECB will probably lobby for governments to improve the country’s €110bn programme. But with euroscepticism rising in Germany and elsewhere, its appeals may fall on deaf ears and pressure for other ways to relieve Athens’ debt burden would build.
The ECB fears an orderly restructuring would be hard, if not impossible, to pull off – and would risk triggering a bigger, far more damaging Greek default. But, says Mr Mayer of Deutsche Bank, its objections suggest “it has not studied the Latin American experience enough”. During the 1980s and 1990s, Latin America learnt difficult lessons on how restructurings could if necessary be implemented.
Policymakers in Frankfurt have not given up the idea that Greece will spare them such a choice. They take comfort from signs of progress this week in Athens on structural reform plans. If Greece does head towards restructuring, the ECB’s only hope will be that its cataclysmic warnings were wrong. A blow to the bank’s credibility, for sure – but the stakes are so high, even that would be a relatively small price to pay.
A Greek Default Won’t Be ‘Contained’, John Mauldin Says
by Aaron Task - Daily Ticker
Financial markets shuddered Monday as fears over Europe's sovereign debt crisis resurfaced yet again. Still, the Dow closed off its worst levels of the session amid the conventional view that Greece's debt crisis can be managed.
But Endgame author John Mauldin says Greece won't be any more "contained" than subprime mortgages were in 2008. "It's not something that stops at the European waters," Mauldin says. "Just like the subprime crisis didn't stop in California…I'm worried this one has a lot of contagion and it'll affect the world."
As for the mechanism for that contagion, Mauldin lays out the following scenario in the event of a Greek default:
- Greece has to nationalize its banks.
- Greek citizens are forced to take deposits in drachmas, rather than euros.
- Greek consumers and businesses then default on all debts because of the resulting haircut, which he estimates at 50%.
- French and German banks are forced to take write-downs on their Greek exposure.
- The ECB is forced to take a write-down on its exposure to Greek debt.
Such a scenario would not go unnoticed in Portugal or, especially, Ireland, where voters have already shown their displeasure with having to pay for bank bailouts, Mauldin notes.
Meanwhile, U.S. banks have written credit-default swaps to European banks. Most of these positions are hedged but "you're only balanced as long as both of those counterparties are good," Mauldin says. "If you have a bad counterparty, now you're out of balance."
If you'll recall, it wasn't the failing subprime mortgages per se that caused the real crisis in 2008, but banks refusal to trade with other banks. It was this "counterparty risk" which caused the financial system to seize up, which is why policymakers here and in Europe are doing everything and anything to prevent a repeat.
Europe's Split on Debt Crisis Hardens
by Charles Forelle and Brian Blackstone - Wall Street Journal
Central Banker Calls Greece Restructuring 'Horror Scenario' in Debate Over Solutions That Is Reigniting Investors' Fears
The dispute between Europe's central bankers and politicians over how to deal with Greece's worsening financial problems intensified, as one of the European Central Bank's top officials rejected calls by Germany and other euro-zone states for a restructuring of Greek debt—calling it a "horror scenario." The comments from Bank of France Governor Christian Noyer, a member of the ECB's governing council, mark the latest salvo in an increasingly heated debate that is fueling fears among investors that the region's debt crisis has entered a dangerous new phase.
The standoff—which has pitted Europe's central bank against Germany and several other euro-zone governments—cuts to the heart of a question at the center of the region's 18-month crisis: how much are the euro area's wealthier members willing to pay to keep the bloc intact.
At issue is whether Greece, barely a year after receiving a €110 billion ($155 billion) bailout, should be forced to default on its obligations or if Europe should extend it more aid. The ECB worries about the consequences even a mild debt restructuring could have on Ireland and other weak euro-zone countries, while leaders in the currency bloc's strong economies, foremost Germany, fear the political cost of further bailouts.
Moody's Investors Service on Tuesday also warned about the consequences of restructuring, saying any Greek debt default would likely torpedo the country's credit for a "sustained" period, possibly thrusting Greek banks into default and leaving other weak euro countries "struggling" to stay out of junk territory.
The head of France's Société Générale, one of Greece's creditors, echoed the restructuring concerns, saying it would be difficult to convince investors that Greece was a one-off. There are consequences for "how the market will look at the European Union and each country," Société Générale Chief Executive Frédéric Oudéa said in an interview. "In my view, the issue is not really just the Greek issue."
The outcome in Greece could hit Ireland, which was forced to seek a bailout last year. Ireland's government is less indebted that Greece's, but its banking system is fragile and fears of debt restructuring could reignite the crisis there.
The disagreement within Europe's leadership revolves around a basic question: What to do as Greece, again, runs out of money? There is broad agreement in Europe that the €110 billion granted last spring isn't enough to get Greece through next year. But there is practically no agreement on how to plug the gap.
Under intense political pressure, leaders in Europe's stronger economies are deeply reluctant to simply write another check. That, many fear, would put the euro zone too far down the road to a fiscal union, in which strong countries have no alternative but to pay for weak countries. Instead, Berlin and its allies want Greece and other weak countries to repair their finances through deep spending cuts and debt restructuring.
The ECB's position is that Greece's financing shortfall must be filled by other euro-zone countries once Athens has exhausted all options for paring its budget and selling its state assets—not by delaying or reducing payments to creditors.
But several key European finance ministers, including Wolfgang Schäuble of Germany and Christine Lagarde of France, have left the door open to a so-called reprofiling of Greece's debt. Under that scenario, Greece's private creditors would be asked to accept repayment later than expected, to help Greece cover its fiscal holes in 2012 and 2013. Such a rescheduling would lessen—or, in an optimistic scenario—obviate the need for European governments to pay for a second bailout. At the least, a reprofiling would mean that private-sector creditors feel some pain, along with taxpayers.
Since the debt crisis emerged in early 2010, nearly all of official Europe had maintained a euro-zone debt default of any flavor was unthinkable. National leaders feared a loss of prestige and a hit to confidence in the region. ECB officials feared the Continent's fragile banks, unprepared for losses on what they had thought were ultra-safe investments, could collapse. But as national leaders have faced the consequence of that position—that preventing a euro-zone debt default means they must always be ready to write more bailout checks—they have backed off.
In Germany, the bloc's strongest economy, the political mood has long been one of antipathy toward further bailouts. But the mood in Europe was shifting more broadly this spring. A right-wing Finnish party made big gains in an electoral campaign by fiercely opposing bailouts. The party didn't win, but it forced Finland's government to tread carefully in talks over revamping the European Union's various bailout funds. As a result, final decisions on those funds—expected as part of a "grand bargain" in March—have not materialized.
Mr. Schäuble was among the first key politicians to suggest a reprofiling of debt could be considered. Ms. Lagarde later joined him, and at a meeting of European finance ministers last week, so did Luxembourg Premier Jean-Claude Juncker, who heads the group of 17 ministers.
The ECB rejects such calls. "Under the ECB's own narrow interest, there is perhaps no better option than to have the whole of the burden being borne by fiscal authorities—Greek taxpayers and taxpayers of the euro zone," instead of by banks who hold Greek debt, says Sony Kapoor, managing director of Brussels-based think tank Re-Define. But given the broad political opposition, Mr. Kapoor says, ECB officials have "unfortunately painted themselves into a corner."
Mr. Noyer of the ECB said that if there were a restructuring, Athens's debt would no longer be accepted as collateral for ECB loans—echoing threats last week by ECB executive board member Jürgen Stark and Bundesbank President Jens Weidmann, both of Germany. Those ECB loans are a lifeline to Greek banks, which borrowed €88 billion from the ECB in March alone. Suspending them would bring the Greek banking system to its knees.
Unlike one year ago, when a cacophony of voices from the ECB on issues such as government bond purchases added to confusion in financial markets, the ECB board is speaking out with unanimity against debt restructuring of any kind.
In the past, officials have reversed similar pledges. Last year, they suspended minimum investment-grade ratings requirements for Greece weeks after ECB President Jean-Claude Trichet said he would make no such exceptions, and bought Greek government bonds days after Mr. Trichet said the idea hadn't been discussed. Many analysts think the ECB could come up with a similar solution and keep funding Greece's banks even if the country is forced to default.
The ECB has pushed hard before. In November, with Irish authorities resisting a bailout, ECB officials threatened to pull the plug on an emergency-lending facility that was helping keep Irish banks afloat. Ireland soon accepted the aid. And ECB pressure has been sufficient to squelch talk of the Irish state's defaulting on the debt of now-state-controlled banks—despite the electoral victory of a party that advocated just that. As a consequence, Irish taxpayers are pouring money into the hobbled banks so they can repay their loans.
Few believe the ECB would cut off Greek banks entirely. But ECB officials maintain a default changes everything, and making an exception for default-rated collateral would put the ECB's balance sheet, and eventually taxpayer money, at risk.
Greece crisis worsens amid political stalemate
by Philip Aldrick - Telegraph
A damaging political stalemate is threatening to plunge Greece deeper into crisis as hopes of cross-party support for further austerity measures were dashed on Tuesday by the main opposition leader.
Antonis Samaras, head of New Democracy, the conservative party that earlier this month called for a renegotiation of the original €110bn (£95bn) bail-out, said he would not support additional austerity measures, totalling €6bn, to reduce the country's budget deficit. His refusal to back the government could jeopardise both payment of the rescue package's next instalment, of €12bn due in June, as well as ongoing talks over a second bail-out, of as much as €60bn.
The political wrangling came as Vince Cable, the Business Secretary, became the first UK politician to admit openly that Greece has no option but to restructure its €330bn of public debt. "What they are going to have to do is to have a rescheduling of their debt and it can be done in a soft way or a hard way, and that's what the current debate is about," he said in a newspaper interview. "I think in practice what will happen, people are already discussing this, is a negotiated rescheduling. "You can't just deal with this by cutting, cutting, cutting – it does not work."
Greece's debts are expected to hit 150pc of GDP this year, the highest in Europe, on top of a 10.5pc budget deficit. It has already begun retrenchment to reduce the deficit to 7.5pc this year, including €50bn of privatisations.
However, officials from the European Union and the International Monetary Fund (IMF), which put up the original €110bn loan, fear the country will miss its fiscal consolidation targets. The government has proposed a further €6bn of measures to bring the deficit down, but Mr Samaras said on Tuesday: "To this demonstrably mistaken recipe, I will not agree." He has previously backed privatisations but warned that increasing taxes would only push the country deeper into recession.
Cross-party support is vital if Greece is to receive further loan instalments and a second bail-out. Brussels and the IMF have made it clear that "political groups set their disagreements aside". Mr Samaras may be angling for a debt restructuring as Greek politicians have acknowledged it may be unavoidable. But some European officials fear a restructuring could trigger panic in the markets for all peripheral euro sovereign debt and spark a second credit crunch.
A second bail-out is expected to comprise of a fresh loan, further austerity, a fresh commitment on earlier agreements and a "soft restructuring" – or lengthening of the terms of the existing debt. Insurance on Greek debt soared on Tuesday, implying a 71pc chance of default within five years.
BRICs slam European grip on IMF, Lagarde leads race
by Lesley Wroughton and Alexandria Sage - Reuters
Top emerging economies joined forces to slam Europe's "obsolete" grip on the IMF's top job, even as France's finance minister appeared to strengthen her lead in the race to replace Dominique Strauss-Kahn.
Brazil, Russia, India, China and South Africa, known as the BRICs, sharply criticized European officials on Tuesday for suggesting the next International Monetary Fund head should automatically be a European. In the first joint statement issued by their directors at the Fund, the BRICs said the choice should be based on competence, not nationality, and called for "abandoning the obsolete unwritten convention that requires that the head of the IMF be necessarily from Europe."
French Finance Minister Christine Lagarde plans to announce her candidacy on Wednesday after the European Union agreed to back her, diplomatic sources said. Hours before the BRIC statement was issued in Washington, France's government said China would back Lagarde to succeed Strauss-Kahn who quit after he was charged with sexually assaulting a hotel maid in New York.
Emerging nations say it is time for Europe's 65-year grip on the IMF to be loosened but no clear consensus candidate to represent them has emerged. Mexico's top central banker said some countries welcomed his decision to run, while South Africa and Kazakhstan may put forward their own candidates.
'European Consensus'
Following Strauss-Kahn's resignation, Europe has made clear it wants to stay in charge of the multilateral lender at a time when it is helping to bail out Greece, Ireland and Portugal. "It's a European consensus," Francois Baroin, France's budget minister and government spokesman, told Europe 1 radio. "The euro needs our attention. We need to have the Europeans (on board), the Chinese support the candidacy of Christine Lagarde," he said.
But China's Foreign Ministry said it had no comment on whether Beijing would back Lagarde, a 55-year-old former lawyer, for the job. Sources in Washington have said the United States would back a European, continuing a tradition that also allows an American to run the World Bank.
The United States and European nations jointly have power at the IMF to decide who leads it but securing support from some emerging economies would defuse a potentially bitter row over the decision. In April 2009, the Group of 20 leading nations endorsed "an open, transparent and merit-based selection process" for heads of the global institutions.
France, which presides over the G20 this year, has made an effort to reach out to Beijing on key issues for developing countries like global monetary reform and speculation in commodity markets. Last week, the head of China's central bank, Zhou Xiaochuan, said the IMF's leadership should reflect the growing stature of emerging economies. But he stopped short of saying its new boss should be from an emerging economy.
Wu Qing, a researcher with the Development Research Centre government think tank in Beijing, said it was plausible that China would support Lagarde as there weren't many qualified candidates from China or Asia in general. The IMF's board will draw up a shortlist of three candidates and has a June 30 deadline for picking a successor.
'Part Of The Process'
Emerging economies say a backroom deal under which Europe maintains its grip on the IMF and an American heads the World Bank could undermine the legitimacy of the institutions. Mexico's Carstens told Reuters the United States welcomed his participation in the race for the IMF job but was neutral on whether to support his candidacy. "They welcomed that I was participating and they thought it was an important part of the process," Carstens said. Brazil seemed reluctant to back Carstens, with government sources saying he is seen as a long shot for the job.
South African Finance Minister Trevor Manuel may also be a candidate to run the IMF, and Russia has said it would back Kazakhstan's central bank chief, Grigory Marchenko. A growing concern about Lagarde is a possible legal probe of her role in a 2008 payout to a prominent French businessman to settle a dispute with a state-owned bank. Judges are due to rule on June 10 -- the deadline for when countries must submit candidates for the IMF job -- whether to launch an inquiry into the matter.
No more bailouts put UK's biggest banks in danger of ratings downgrades
by Alex Hawkes - Guardian
Ratings agency Moody's put Lloyds TSB, Royal Bank of Scotland and Santander UK on review for possible credit rating downgrades, saying that there will be no taxpayer-funded bailouts in the future. The three are the most high-profile of fourteen banks and building societies put under review by the agency. The review relates to the financial institutions' senior debt and deposit ratings.
"The reassessment is not driven by either a deterioration in the financial strength of the banking system or that of the government. It has been initiated in response to ongoing guidance from the UK authorities (the Bank of England, the Financial Services Authority and the Treasury) that banks that fail in the future should not expect capital injections from the public purse," said Elisabeth Rudman, a Moody's senior credit officer and bank analyst.
The move by Moody's could lead to a hike in the banks' borrowing costs. The review process will take three months. The banks and building societies covered by the review are: Bank of Ireland; Co-operative Bank; Coventry Building Society; Lloyds TSB; Nationwide Building Society; Newcastle Building Society; Norwich & Peterborough Building Society; Nottingham Building Society; Principality Building Society; Royal Bank of Scotland; Santander UK; Skipton Building Society; West Bromwich Building Society; and Yorkshire Building Society.
The move follows an announcement from Moody's last month that it would reassess the levels of systemic support incorporated in the senior debt ratings of UK financial institutions. Moody's will conduct a full review of the levels of government support available, and any other mitigating factors that could obviate the need for a downgrade. It said that it was reviewing the situation because the current long-term ratings on banks involved levels of government support "that the rating agency may now deem to be too high for the evolving post-crisis environment".
Moody's said: "The authorities have taken a number of legislative and other steps to permit losses to be imposed on creditors as part of the going-concern resolution of banks. While we note – and will take into consideration – the technical difficulties in resolving larger, complex banks, we will also need to assess the likelihood of further developments in this area over the medium term, given the very clear determination of the UK government to put in place a resolution mechanism that can also be applied to large, complex banks," Rudman said.
Government support accounts for an uplift of two to five notches for the big banks, and one to five for the smaller institutions. "Moody's expects to retain a high level of systemic support uplift in the senior debt ratings of the major UK banks, as the rating agency believes that the regulators do not currently have all the tools necessary to resolve such institutions without causing financial instability," it said.
The announcement also said that Barclays has been changed to negative from stable, and that HSBC's rating has been affirmed with a negative outlook. Barclays and HSBC are not under review but have suffered a hit, Moody's said, because the government has publicly stated it believes senior debt holders should share the pain if the banks get into trouble.
China seen as the candidate for 'next catastrophe'
by Helia Ebrahimi - Telegraph
Beware the China bubble because until hedge funds have found a way of directly shorting the soaring economy it will remain unchecked, says Greg Zuckerman, author of The Greatest Trade Ever. Mr Zuckerman's book was one of the first to reveal the billions in profits which hedge funds and banks from taking bets against the sub-prime market just before the housing bubble burst.
China, where the economy has expanded 10.1pc a year on average since 1978, is reminiscent of the housing market before credit default swaps allowed hedge funds to make bets against the entire market, according to Mr Zuckerman.
When China's growth will decelerate or come to an abrupt stop is probably the most critical question facing the world economy. But predictions of a hard landing on everything from bad loans to investment-led overheating or inflation has yet to derail the country's expansion.
This is because the government-controlled economy is insulated from speculators testing the true voracity of the market, claims Mr Zuckerman. "We need short sellers," he said. "The problem with the housing bubble was that for a long time people couldn't bet against it. Credit default swaps gave hedge funds specific tools to short the entire market. That pricked the housing bubble. "It is very difficult to make a direct bet against China. You can short property companies in Hong Kong but it is not the same thing. It is a candidate for the next catastrophe."
Risk From Spent Nuclear Reactor Fuel Is Greater in U.S. Than in Japan
by Matthew L. Wald - New York Times
The threat of a catastrophic release of radioactive materials from a spent fuel pool at Japan’s Fukushima Daiichi plant is dwarfed by the risk posed by such pools in the United States, which are typically filled with far more radioactive material, according to a study released on Tuesday by a nonprofit institute.
The report, from the Institute for Policy Studies, recommends that the United States transfer most of the nation’s spent nuclear fuel from pools filled with cooling water to dry sealed steel casks to limit the risk of an accident resulting from an earthquake, terrorism or other event.
“The largest concentrations of radioactivity on the planet will remain in storage at U.S. reactor sites for the indefinite future,” the report’s author, Robert Alvarez, a senior scholar at the institute, wrote. “In protecting America from nuclear catastrophe, safely securing the spent fuel by eliminating highly radioactive, crowded pools should be a public safety priority of the highest degree.”
At one plant that is a near twin of the Fukushima units, Vermont Yankee on the border of Massachusetts and Vermont, the spent fuel in a pool at the solitary reactor exceeds the inventory in all four of the damaged Fukushima reactors combined, the report notes.
After a March 11 earthquake and tsunami hit the Japanese plant, United States officials urged Americans to stay at least 50 miles away, citing the possibility of a major release of radioactive materials from the pool at Unit 4. The warning has reinvigorated debate about the safety of the far more crowded fuel pools at American nuclear plants.
Adding to concern, President Obama canceled a plan for a repository at Yucca Mountain in the Nevada desert last year, making it likely that the spent fuel will accumulate at the nation’s reactors for years to come. The Nuclear Regulatory Commission maintains that both pool and cask storage are safe, although it plans to re-examine the pool issue in light of events at Fukushima.
Nearly all American reactors, especially the older ones, have far more spent fuel on hand than was anticipated when they were designed, Mr. Alvarez, a former senior adviser at the Department of Energy, wrote.
In general, the plants with the largest inventories are the older ones with multiple reactors. By Mr. Alvarez’s calculation, the largest amount of spent fuel is at the Millstone Point plant in Waterford, Conn., where two reactors are still operating and one is retired. The second-biggest is at the Palo Verde complex in Wintersburg, Ariz., the largest nuclear power plant in the United States, with three reactors.
Companies that run reactors are generally reluctant to say how much spent fuel they have on hand, citing security concerns. But Mr. Alvarez, drawing from the environmental impact statement for the proposed repository at Yucca Mountain, estimated the amount of radioactive material at all of the nation’s reactors.
In the 1960s, when most of the 104 reactors operating today were conceived, reactor manufacturers assumed that the fuel would be trucked away to factories for reprocessing to recover uranium. But reprocessing proved a commercial flop and was banned in the United States in the 1970s out of concerns that the plutonium could find its way into weapons worldwide.
Today roughly 75 percent of the nation’s spent nuclear fuel is stored in pools, the report said, citing data from the Nuclear Energy Institute. About 25 percent is stored in dry casks, or sealed steel containers within a concrete enclosure. The fuel is cooled by the natural flow of air around the steel container.
But spent fuel is transferred to dry casks only when reactor pools are nearly completely full. The report recommends instead that all spent nuclear fuel older than five years be stored in the casks. It estimated that the effort would take 10 years and cost $3.5 billion to $7 billion.
“With a price tag of as much as $7 billion, the cost of fixing America’s nuclear vulnerabilities may sound high, specially given the heated budget debate occurring in Washington,” Mr. Alvarez wrote. “But the price of doing too little is incalculable.”
The casks are not viewed as a replacement for a permanent disposal site, but as an interim solution that would last for decades.
The security of spent fuel pools also drew new attention after the attacks of Sept. 11, 2001, partly because one of the planes hijacked by terrorists flew down the Hudson River, over the Indian Point nuclear complex in Westchester County, before crashing into the World Trade Center in Manhattan.
Indian Point has pressurized water reactors with containment domes, but its spent fuel pools are outside the domes. The pools themselves are designed to withstand earthquakes and other challenges, but the surrounding buildings are not nearly as strong as those that house the reactors.
In a 2005 study ordered by Congress, the National Academy of Sciences also concluded that the pools were a credible target for terrorist attack and that consideration should be given to moving some fuel to dry casks.


