


"Abandoned garage on Highway No. 2, Western North Dakota"
It's coming from the sorrow in the street,
the holy places where the races meet;
from the homicidal bitchin' that goes down in every kitchen
to determine who will serve and who will eat.
From the wells of disappointment where the women kneel to pray
for the grace of God in the desert here and the desert far away
Democracy is coming to the U.S.A.
- Leonard Cohen: Democracy
Ilargi: I've left the American debt ceiling debate be for the most part so far because I’m not that interested in people jockeying for election time positions while engaging in kindergarten level "fights". Now that the August 2 deadline is just one week away, we’ll look at the specifics a bit more over the course of the coming days. But not with a focus on what the Washington elite is actually saying; that stuff just bores me.
Instead, I want to shift towards what the inevitable last-minute agreement will mean for the people on the ground. And that will not be pretty. It will be harsh austerity, even if US politicians -and likely media too- will shy away from using the term. Let them. Let them reserve it for what happens in Greece and Ireland if that makes them feel better. A rose by whatever name and all that. Just don't let that fool you.
Today it's the US Postal Service closing down 3700 additional offices. Tomorrow it will be Social Security, Medicare and so on and so forth. Last week we saw that the Federal Reserve has spent $16 trillion on bailouts thus far this crisis. The debt ceiling debate is being used as we speak as the first tool to make ordinary Americans pay for this. It's no different from what's going on in Athens and Dublin, and soon Lisbon, Madrid and Rome. The MO of the political/financial system that holds all the levers in our societies is based on a wealth transfer going one way, and a debt transfer going the other.
This is the essence of the Greek rescue operation set in motion last week in Europe, and it's the essence of the debt ceiling debate. A lot of preliminary talk about the terrible outcome if things are not done the proper way, followed by agreements that make the financial markets happy, however shortlived, and put populations into ever deeper misery. The trick is that this misery is always transferred to the future, so while the documents are signed, nobody notices right away.
But then that future arrives, and sooner than anticipated by most; the insatiable markets will from now on go after anyone who shows a weakness. And demand more money. This is how entire societies are being gutted.
Here's Ashvin with a picture of austerity in Europe. This is what's coming to America, and much more too.
needs your support
Donate to our Summer Fund Drive!
Ashvin Pandurangi:
Part I - The Greek & The Irish

"Stroll through the shanties, and the cities remain.
Same bodies buried hungry, but with different last names.
These vultures rob everything, leave nothing but chains.
Pick a point on the globe; yes the picture's the same.
There's a bank, a church, a myth and a hearse;
a mall and a loan, a child dead at birth.
There's a widow pig parrot, a rebel to tame,
a whitehooded judge and a syringe and a vein.
And the riot be the rhyme of the unheard..."
Rage Against the Machine: Calm Like a Bomb
Rage is deeply-rooted fear and frustration metastasized in the body of a global and institutionalized society; the natural result of economic disenfranchisement. It is one thing to advocate in the name of rage, another to predict that episodes of collective rage will occur and yet another to note that they are already occurring and accept them as a fundamental aspect of our lives. The former should be avoided as much as possible, while the latter two are required of the responsible analyst, in my humble opinion. "RATM" may not be a shining beacon of objective analysis in our world, but, at the same time, they are right.
People across the world are once again recording their "rhymes" as history unfolds. The debt-drugs were injected for years on end, so now the only question is how far down the revolutionary river our rage-filled, junkie mentality will carry us? Southern Europe (and Ireland), of course, are back in the cross-hairs right now, to the extent that poorer parts of the world ever escape them. Revolutions were all but manufactured by Western colonial/imperial powers in Latin America, Asia, Africa and the Middle East throughout the 20th century (see The Shock Doctrine and Confessions of an Economic Hitman), but now the chickens are coming home to roost.
The last time Greece had a true "revolution" (let's call it "a widespread uprising of the people which displaces or severely threatens the existing political order") was in the 1820s, Spain was in the 1860s, Italy in 1848, Ireland in 1916 and Portugal the most recent in 1974 (no shots were fired in this military coup). [1], [2]. In the case of France, Germany and the UK, the populations have generally suffered their own governments for much longer stretches with fewer internal uprisings. Now, in the span of just over a year, we have witnessed mass protests and/or riots in all of these countries, on multiple different occasions.
The trigger for this rage has largely been either the establishment and/or proposal of "austerity measures", as both conditions of EU "bailouts" or independent fiscal policy, or the subsidization of debtor nations by those belonging to Europe's "core". This situation in the EMU has created an extremely tense dynamic both within and between the respective populations of member states. So if we want to know the future of social unrest in Europe, perhaps we should look to the future of bailouts and austerity. To date, the two countries in the developed world that are facing the most severe austerity measures are, without a doubt, Greece and Ireland.
GREECE

After the first round of Greek bailouts last year, its public bond yields were back to all-time highs as its economy had contracted from conditioned austerity and its finances remained dismal. The new plan concocted last week in the European "Leaders' Summit" has allowed Greece's 2-year bond yield to retrace about 1300 basis points (from above 40% to just over 27%), as it calls for further subsidization of Greek debt and "voluntary" bond swaps by private investors in Greek bonds. The latter, of course, will not be termed an act of "default" by any of the relevant institutions, except maybe the rating agencies (who would be surprised if they caved?), despite that being exactly what it is.
It is estimated that bondholders who participate in this swap program into longer-term bonds will take losses of up to 21% on the net present value of their current instruments. [3]. These alleged "haircuts" are not only a gigantic under-appreciation of Greek's insolvency, but will most likely still be subsidized by European workers and taxpayers, as investors put those "government guaranteed" bonds to the ECB as collateral. John Maudlin describes this dynamic in his latest E-Letter, Kicking the Can Down the Road One More Time:
"Here is what it [the latest EMU plan] really says: We are going to keep throwing good money after bad and work as hard as we can to transfer the debt that is on the banks to the ECB and European taxpayers as long as the voters will let us. This first tranche will be another €109 billion. That will last a few years, and Greece will only have to pay about 3.5% on that debt and the rollover debt, and people who expected to be repaid in that period will see payment extended to either 15 or 30 years.
You can call this what you like, and they call it "selective default,” but it is a default. There will be government guarantees on the debt, so the ECB can take it from the banks. Let’s see what the "voluntary” debt rollovers will look like and what the likely debt destruction will be. This is from Global Macro Monitor.
First, notice that the plan claims haircuts will only be 21%. But that assumes you can sell the new bonds at a 9% interest rate. If the interests rate demanded by the market are 15%, which is closer to reality, the haircuts are closer to 67%, after what appears to be an initial 20% cut. Will any institution not immediately try and get those bonds into the hands of the ECB? This is just ugly."
Ashvin Pandurangi: So how much will major bondholders really have to share in the losses on risky debt-instruments that they generated in the past, and how much of those losses will be immediately pawned off to the ECB under the new plan? Many of the details of this new "fiscal consolidation" of the EMU have yet to be ironed out, and it is still not clear whether it will be accepted as drafted by the relevant Parliaments. Ambrose Evans-Pritchard writes on this issue in The Telegraph:
"The terms overstep a resolution passed by the Bundestag limiting how far she [Merkel] could go in committing Germany to any form of transfer union or pooling of debts. The use of the EFSF as a fiscal fund without treaty authority further complicates a ruling by the German constitutional court on the legality of the bail-outs expected in September. Such changes to the EFSF will require ratification by each of the national parliaments. It may require an amendment to the Treaties, greatly raising the bar in Germany.
EU officials hope that a debt rollover plan for Greece can be limited to a short technical default. The ECB has backed down on its threat to reject Greek bonds as collateral. The formula will not be extended to Portugal and Ireland. It is understood that rating agencies will hold fire for the sake of global stability. However, there is no disguising that a major taboo has been broken, even if French leader Nicolas Sarkozy continued to insist that Greece would pay "all its debts"."
Ashvin Pandurangi: So, it is still unclear to what extent the new "stability" mechanisms will be implemented across the EMU, but Evans-Pritchard is right to say that a major line has been crossed, regardless of the final details. There is no doubt that the Emergent Union, through its latest plan, has now decided to stick together until the bitter end, when death finally does them apart. We are talking about the unilateral decisions of political and financial officials, though, which are not even close to being reflective of what their populations want. Nowhere is that fact more true right now than in Greece.
At least 95% of the Greek people are suffering immensely to remain in a Union that fails to benefit anyone outside of the top 5%. The authorized plans for austerity and privatization of the citizens' assets continues unabated, and more ominous than ever. Any backstops of Greek debt in the future will still be accompanied by austerity measures approved by the Greek government earlier this month. Meanwhile, the government is still in the process of finding new "advisers" (investment banks) to pay hefty fees in return for advice on how to reduce their deficit via asset sales. [4]. Jeremy Warner from The Telegraph reports:
"Agreement on the package is one thing, deliverability is quite another. Once Germans realise that what is being proposed is a transfer union by stealth, you have to wonder what political future there is for the leaders who agreed it. Angela Merkel is staring election defeat in the face, rather in the way that agreeing to German participation in the euro was arguably what did for Chancellor Helmut Kohl back in the late 1990s.
The same might be said of the recipient nations. What future for political and social stability among the newly enslaved once it is realised the price that has to be paid is loss of fiscal sovereignty together with years of externally imposed austerity;
The agreement refers to a "European Marshall Plan” to restore competitiveness to Greece. This doesn’t appear to mean money. Instead it seems to refer to the provision of "exceptional technical assistance to help Greece implement its reforms”. In other words, someone else will be running Greece’s affairs."
Ashvin Pandurangi: How will this hypocritically harsh plan of austerity and privatization sit with the people of Greece? The proposed austerity measures adopted by the Greek government foresee tax increases of about $9B over the next four years, with almost $8B (~90%) front-loaded in the next two. This includes a measure to reduce the income tax threshold 30% (from 12,000 euros to 8,000) and place a "solidarity levy" on households for 1-5% of income this year. What that really means is the average Greek worker will be paying substantially more taxes, while the wealthiest brackets continue to evade them with relative ease.
Der Spiegel:
"Two-thirds of Greeks regularly pay their taxes as well. Indeed, "contrary to widespread views," as the Friedrich Ebert Stiftung study put it, these taxes are automatically deducted along with social contributions from the paychecks of Greeks employed in both the private and public sectors. It is mainly the small wealthy class that manages to cheat the authorities out of €40 billion in tax each year. That is the OECD's estimated volume of annual tax evasion. The Greek central bank puts the losses at somewhere between €15 billion and €20 billion.
These tax cheats have little to fear. As Panos Kazakos, an Athens-based professor of politics, puts it: "I have never seen a single person put in jail for tax evasion." Robolis adds that the government, which supposedly has no money available for social services, just published a list of companies that owe the state a total of €9 billion in social contributions -- but it does nothing to get that money.
This injustice is what is making people in Greece so angry..."
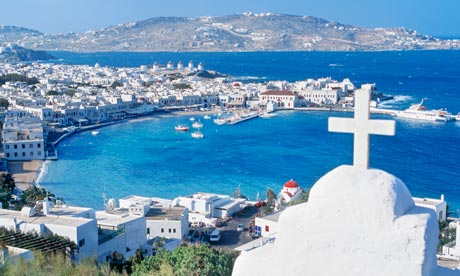
Ashvin Pandurangi: The plan also calls for about a $31B reduction in spending over the same four-year time frame, with a majority coming from a reduction in public salaries, social programs and health care spending. Taken together, these measures amount to more than 10% of Greece's GDP. Such cuts represent a systematic gutting of safety nets that the average Greek has become reliant on for any chance of solvency, and, even survival in some cases. Finally, the proposed plan aims to generate about $70B+ from sales of public assets, including the citizens' stake in sea ports, airports, highways, mining operations and various other property (such as land on the island of Mykonos [6]) until 2015. [7].
UN News Centre:
"The implementation of the second package of austerity measures and structural reforms, which includes a wholesale privatization of state-owned enterprises and assets, is likely to have a serious impact on basic social services and therefore the enjoyment of human rights by the Greek people, particularly the most vulnerable sectors of the population such as the poor, elderly, unemployed and persons with disabilities,” said Cephas Lumina, who reports to the UN Human Rights Council in Geneva.
Ashvin Pandurangi: The UN is generally known for having a lot of opinions on "human rights" issues without ever really backing them up with concrete action, but the statement above still touches on a very important dynamic for the Greek people. More and more of them are entering the "most vulnerable" classification of neo-feudal society, as they are forced to join the ranks of the impoverished and/or the unemployed.
Der Spiegel:
"This time, the fight for survival last exactly 29 minutes. At precisely 3 p.m., Father Andreas, a 37-year-old Greek Orthodox priest, opens the doors of the food bank in downtown Athens. At this hour, the line of hungry people stretches all the way across the large square outside and into the street. Needy people of all ages are waiting patiently -- pensioners, unemployed people, mothers with children, immigrants, asylum seekers. "We can't let these people starve," the priest says. "They are already suffering so much. They should at least not go without food. [..]
In recent weeks, the needs of such people have been keeping Father Andreas and his colleagues very busy. Almost all of the 400 parishes in the Archdiocese of Athens have opened food banks like the one he runs. City officials have opened some as well.
His food bank distributes meals three times at day. Up to 2,000 come at noon, another 1,200 in the afternoon, and about another 1,000 in the evening. The workers try to make sure that they don't always supply the same people. Such vigilance is necessary because "the number of needy is skyrocketing," says one volunteer who estimates that the figure has increased by 30 percent in recent months. "But we can't be sure it will stay there," she says."
Ashvin Pandurangi: It now becomes clear that one cannot and should not under-estimate the revolutionary spirit of an extremely vulnerable population; one which has increasingly less to lose with every iteration of bailouts, austerity and privatization, as was clearly demonstrated by the Greek people at the end of June.
Der Spiegel:
"On Wednesday [June 29] afternoon, tear-gas fumes drifted through the city center. More than 200 demonstrators were reported to have been injured, most of them with eye and respiratory problems. The police union said at least 40 policemen had been injured, one of them seriously. A total of 30 people were arrested. [..]
On Wednesday, one protester, his face covered up, warned that the conflict would continue. "This is just the beginning," he said."
Ashvin Pandurangi: The anonymous protester was absolutely right - those events were only just the beginning of a fundamental and deepening trend for the people of Greece under their new regime of oppressive austerity.
Der Spiegel:
"For weeks, thousands of enraged Greeks have been holding anti-government demonstrations outside Greece's parliament building. They come with bullhorns and banners, and a couple hundred also bring stones and Molotov cocktails. Camera crews from around the world are always there to film them, but they never turn their lenses toward those in the dark back alleys of central Athens."
Ashvin Pandurangi: It is very difficult to look at the proposed austerity measures, in the context of the above developments, and conclude that the rage and riots in Greece will not get much worse. Last year saw its fair share of violence in Athens, and June 29, 2011 did as well, but there is also every reason to think Greece's economic/financial situation will continue to deteriorate as renewed austerity and privatization plans takes their toll. As reported above, that toll is especially pronounced in the "back alleys" of Athens where no one is looking. Instead, they choose to focus on sound bites from international institutions and national politicians who claim to be "saving" the country.
Der Spiegel again:
"Last week, Prime Minister Georgios Papandreou once again succeeded in getting a majority of Greek lawmakers to push through an austerity and privatization package worth €78 billion ($111 billion). In doing so, he was responding to pressure from the International Monetary Fund (IMF), the European Central Bank (ECB) and the European Commission. Indeed, many economic experts see the package's measures as the only way to fend off an imminent national bankruptcy at the last minute -- and the only way to save the euro from an even worse fate.
But is Papandreou saving his country to death? Savas Robolis thinks he is. "People are afraid," the 65-year-old says -- they're afraid of an uncertain future."
Ashvin Pandurangi: This fear of the future will continue to strengthen the sociopolitical backlash against a political and banking system that has unequivocally expressed its disdain for the people of Greece. An increasing number of Greek people are protesting for their right to eat a decent meal every day, but the plans for severe spending cuts, tax increases and public asset sales continue on as if those protesters didn't even exist. In the meantime, European leaders meet with each other and figure out "clever" ways of tying themselves into a tight, inseparable knot of fiscal abandon. And for those two reasons alone, the modern world has yet to see the largest uprising that the Greek populace can produce.
IRELAND

Like Greece, Ireland was also given a conditional bailout last year that has proven to be devastating for domestic economic growth. The new plan presented by EMU honchos says that Ireland will be able to borrow from the ECB at 3.5%, well below market rates (~5.8%), but it is not allowed to "selectively default" just yet. As a part of the conditions to reduce its budget deficit last year, Ireland had developed a budget for 2011 that was the most severe in its national history. Unlike the Greeks, however, the Irish people have so far kept relatively quiet in response to the ever-darkening clouds on their horizon. The Irish novelist Ed O'Loughlin has a theory for why that has been the case, as The Guardian reports:
"Dublin-based novelist Ed O'Loughlin says that perhaps one reason why the Irish are proving so docile is that for the first time in centuries the British can by no stretch of the imagination be blamed for their problems.
The author of the political satire Toploader adds: "The lack of clearly stratified classes – as they have in England – breeds insecurity, a fear of losing caste, of being pushed outward. To protest at the rules of this game would be an admission that you no longer have a hand to play in it; that you are a loser and a sucker."
At times of mass emigration, just staying in the country was felt to be a victory in itself, although often a pretty hollow one. "The fact that everyone's class system is centred exactly on themselves tends to make people, naturally, very self-centred. The Irish term for this is 'mé féin-ism', or 'myself-ism', a play on Sinn Féin, or 'we ourselves'. Mé féiners do not stand together for the common good. They are not good citizens."
Ashvin Pandurangi: It's an interesting theory that may demonstrate the power of a nation's political and cultural history to restrain the socioeconomic frustration of its people, but how long will this dynamic last for the Irish? Before getting to that question, let's first summarize what the people of Ireland are facing in the way of austerity measures. The current budget for Ireland includes spending cuts and tax increases, valued at about $8B, over the next year alone, or 4% of GDP. Most of the reduction in spending will come from cuts to welfare programs and public sector salaries/benefits.
The budget will reduce 4% of public pension expenditures by cutting benefits to retirees who are already being paid out. The tax increases will mostly come from income and value-added tax reform (lowering the income tax threshold and increasing VAT to 23% from 21%), although the top marginal income tax rate will be kept at 52%. The Irish government may also sell "non-strategic" public assets valued up to $3B over time, on recommendations of the "McCarthy Group". [8].
Meanwhile, the corporate tax rate will continue to be held at 12.5% (the lowest rate in OECD countries), which effectively serves to deflect the austerity burden from corporations generating massive profits within the country. [9], [10].

These large corporations paying a meager rate of 12.5% include the same financial institutions that were initially responsible for putting Ireland in a fiscal straight-jacket. It would be foolish to think that this tragic irony is being lost on the Irish people, who may soon be forced to further subsidize their financial industry through the Bank of Ireland, which is the only non-state controlled institution left (the state holds less than 50% of its shares). [11]. Right now, though, it actually appears that the British taxpayers, through the Royal Bank of Scotland, have taken on a part of that role:
The Irish Independent:
"In a statement, the bank [BoI] said it had raised the funds through two "bilateral secured term funding" trades; one yesterday and one at the end of June. The latest trade is believed to have been done with RBS -- itself nationalised by the British government in 2009. The funding, which is not covered by the banking guarantee, has an average duration of some 2.2 years.Although the lender would not comment on all the specifics of the fundraising, they did reveal that under the funding agreement's terms, they will pay 2.65pc above the three-month Euribor rate. [..]
BoI is facing a race against time to avoid joining the rest of the Irish banking sector under state ownership. After the results of the stress tests in April, it was told it had until the end of June to raise €5.2bn if it wanted to remain under private ownership. That deadline was pushed back to the end of this month with the firm trying desperately to raise the required funds."
Ashvin Pandurangi: If and when the BoI loses its race to stay private, it's the Irish taxpayers who will pick up the tab for an extra 2.65% interest on loans from RBS, along with any other obligations passed on by the private banking sector. Considering these developments and the ongoing effects of current austerity measures, it is difficult to see the Irish people remaining "docile" for much longer. There is only a certain amount of restraint that can be imposed by cultural perceptions before the reality of economic desperation sets in. They are now merely remaining "calm like a bomb", and the fuse on that device has been lit.
The Guardian article referenced earlier also includes the following assessment by John Kearns of the Irish Writers Centre:
"John Kearns, who went abroad in previous recessions and now works in Dublin's Irish Writers Centre, says it is too early to rule out social unrest. 'It's quite possible there will be Greek-style riots. The cuts are affecting people now. People are having their utilities cut off. I know of families, a mother of two, who had their electricity cut off. People can't take that lying down.
And there is still a mortgage crisis coming down the track with increasing interest rates that are coming later this year. I can certainly see social unrest ahead, although I don't see what can be achieved by it. It's strange that the main demonstrators so far have been pensioners and students rather than industrial workers. The workers so far have been far quieter,' Kearns said."
Ashvin Pandurangi: Indeed, there are strict limits to the amount of economic hardship a population can take before its "restraint" comes to be perceived by it as an exercise in futile despair. It appears that there is now very little standing in the way of fear and rage taking over the reigns of the Irish sociopolitical system. A recent survey found that the Irish people are beginning to agree with Kearns in massive numbers, whether they are truly aware of it yet or not.
Irish Examiner:
"In the last survey, 36%, or 428,000 people, did not see a future for themselves or their family in this country. However, this has now risen to 45% or 585,000. The iReach survey for the Irish League of Credit Unions (ILCU) found that 82%, or one million adults, fear about coping if further changes to income tax or welfare are introduced.
The survey found that 806,000 people feel they are living to work as opposed to working to live. However, the latest results have not factored in the July interest rate hike and in March one-in-five people said that a hike would have a serious effect on their ability to pay bills."
Ashvin Pandurangi: Well over half a million Irish people and families see "no future" living in their own country, and a solid million adults fear for their ability to make ends meet in the current climate of unaffordable private debt and public bailouts conditioned with severe austerity. That is quite simply a recipe for wide-scale protests, riots and uprisings in the near future. It is fundamentally impossible to predict exactly when such fervor will materialize, or what intervening factors will delay its development, such as Irish politics and culture, political/legal maneuvers by EU governments, financial maneuvers by the IMF/ECB, etc.
However, at the end of the day, these factors are only strengthening the population's future resolve. They are merely extending Ireland's exposure to the bailout structure of the EMU, and the numerous conditions that naturally accompany those bailouts. The fact that EU leaders are now planning to consolidate that structure under the modified ESFS, abandoning the haphazard process they had earlier, changes nothing for the Irish people. Eventually, they will need to write off a portion of the bad debts taken on by their government, just like the Greeks, and they will be forced to pay the price through further austerity and privatization.
I have noted before, in The Short Story of How We Lose, that the pain of losing is disproportionately more severe than the pleasure of winning. Similarly, the relatively abstract prospect of losing in the future is not nearly as painful as the act of losing itself. As the proposed austerity measures targeting the Greek and the Irish transform into implemented measures and real losses for their pocketbooks, we can expect the fear and rage to follow closely behind. Many of the remaining chords tying the people to their political structures will be severed. And, lest anyone tell you different, collective rage is largely a function of deeper socioeconomic trends; ones that are now common to the entirety of Europe and the developed world.
US lawmakers head for showdown in debt crisis
by Andy Sullivan and Matt Spetalnick - Reuters
President Barack Obama's Democrats and their Republican rivals on Tuesday headed for a showdown over competing debt plans one week before a deadline for averting a potentially disastrous U.S. default.
With the two sides further apart than ever and the threat of a far-reaching U.S. credit downgrade looming, IMF chief Christine Lagarde urged swift resolution of the impasse, warning that failure to reach an agreement would have serious consequences for the world economy. "The clock is ticking and clearly the issue needs to be resolved immediately," Lagarde told the Council on Foreign Relations think tank.
But there was no compromise in sight after Obama and Republican House of Representatives Speaker John Boehner delivered dueling televised addresses late on Monday and gave no ground in the bitter debate over how to raise the nation's $13.4 trillion debt ceiling by August 2 to prevent an unprecedented default.
The continuing gridlock -- and signs that neither of the competing plans is likely to win bipartisan support -- alarmed investors worldwide. U.S. stocks and the dollar fell while gold hovered near record highs. But there was no hint of panic as the financial markets held out hope that the stalemate could still be broken.
Boehner on Tuesday kept up efforts to rally support for his plan, which could come up for a vote in the House as early as Wednesday but is in doubt because of resistance from some conservatives in the Republican camp aligned with the Tea Party movement. "It's reasonable, it's responsible. It can pass the House and it can pass the Senate," Boehner told reporters.
Boehner is pushing a two-stage deficit reduction plan that would start with an initial $1.2 trillion in savings over 10 years. Obama opposes it because it would raise the debt limit for only a few months, something he has said he will not agree to. The chief Democratic vote counter in the House, Representative Steny Hoyer, said "maybe a few" Democrats would back Boehner's plan. That would boost the bill's chances in what is expected to be a close vote on Wednesday.
Obama's Democrats have presented their one-step plan for $2.7 trillion in deficit reduction over the next decade but with a debt limit hike that would carry through the November 2012 elections, when he is seeking a second term. Senate Majority Leader Harry Reid, a Democrat, is expected to hold off on any vote on the plan until the House takes up Boehner's proposal.
Far Apart
Republican and Democratic lawmakers, despite weeks of intense talks, are far apart on a deal to reduce the budget deficit, which would clear the way for Congress to lift the debt ceiling by next week, when the country runs out of cash to pay all of its of its bills. Democrats control the Senate. Republicans control the House of Representatives.
Credit rating agencies have threatened to downgrade America's top-notch Treasury bonds if a rise in the debt limit is not accompanied by plan for controlling long-term deficits. A default and downgrade could push the United States back into recession and create global financial chaos. A key element of the standoff has been congressional Republicans refusing to allow any tax increase in deficit reduction packages.
Obama said in his Monday address a default would inflict the equivalent of a tax hike on all Americans by pushing up borrowing costs on things like credit card loans and mortgages, but he sought to assure markets a deal could be reached. "I have told leaders of both parties that they must come up with a fair compromise in the next few days that can pass both houses of Congress -- a compromise I can sign. And I am confident we can reach this compromise," he said in his speech.
Markets responded warily to Obama's remarks. Major U.S. stock exchanges were down less than half a percent in early trading. The dollar fell across the board, hitting a record low against the safe-haven Swiss franc. Gold, seen as another safe haven from the American and European debt woes, rose to a record high on Monday and hovered near that level on Tuesday. However, financial markets are not showing any sign of panic.
Obama to Banks: We're Not Defaulting
by Charlie Gasparino - FOXBusiness
While officials from the Obama Administration raised their rhetoric over the weekend about the possibility of a debt default if the debt ceiling isn't raised, they privately have been telling top executives at major U.S. banks that such an event won’t happen, FOX Business has learned.
In a series of phone calls, administration officials have told bankers that the administration will not allow a default to happen even if the debt cap isn't raised by the August 2 date Treasury Secretary Tim Geithner says the government will run out of money to pay all its bills, including obligations to bond holders. Geithner made the rounds on the Sunday talk shows saying a default is imminent if the debt ceiling isn't raised, and President Obama issued a similar warning during a Friday press conference after budget negotiations with House Republicans broke down.
While the negotiations to craft a budget remain at an impasse, Republicans and Democrats on Monday began crafting their own plans to cut spending that could lead to an agreement to raise the debt ceiling. It's unclear if a broad agreement can be reached any time soon, but even if a deal is struck, a complicating issue for lawmakers and the administration is the possibility of a downgrade to the US debt rating, which would cut the triple-A rating on the nation's debt to a lower level.
Major ratings firms -- namely Standard & Poor's and Moody's -- have said even if the country raises the debt ceiling and doesn't default, there's a strong likelihood that the triple-A bond rating will be cut to double-A unless a budget can be crafted that results in $4 trillion in savings, the result of the massive debt load the country has accumulated in recent years. The nation's outstanding debt is more than $14 trillion.
A senior banking official told FOX Business that administration officials have provided guidance to them that even though a default is off the table, a downgrade "is a real possibility for no other reason than S&P and Moody's have to cover (themselves) since they've been speaking out on the debt cap so much."
This guidance is a big reason why Wall Street has largely dismissed the possibility of default, and though the markets have been jittery amid the talk of default, they haven't imploded as would be the case, many economists fear, if the nation missed a payment on its debt. The banking official said the administration understands that if there were to be a default, it would likely spark another financial crisis.
"They also know they can pay the debt with cash on hand," this official told FOX Business. The Treasury collects around $2 trillion in tax revenues, and is scheduled to pay out $200 billion in interest to bond holders. In order to meet its obligations to contractors, social security recipients and others, the administration would have to raise another $1 trillion either through cuts, higher tax revenues, the issuance of debt or a combination of all three.
Congressional Republicans believe that the Administration is raising the possibility of a default as a way to ramp up pressure on Republicans to agree to a budget deal that includes tax increases, which they oppose. A Treasury spokesman said that "when we exhaust our borrowing authority, as we will on August 2nd, there is no way to guarantee that we will be able to pay all of our bills. Any suggestion to the contrary is simply false."
Even without a default, banks expect some market turbulence if the triple-A sovereign-debt rating is cut, sources tell FOX Business. While bank officials do not believe there will be a “catastrophic” effect to a downgrade, that’s not to say there won’t be negative ripple effects, notably to bond deals and derivatives priced off triple-A-rated Treasurys.:
Home Prices in 20 U.S. Cities Fell 4.5% in Year Ended May
by Bloomberg
Home prices in 20 U.S. cities dropped in the year ended May by the most in 18 months, adding to evidence the housing market is struggling. The S&P/Case-Shiller index of property values in 20 cities fell 4.5 percent from May 2010, the group said today in New York. The decline matched the median forecast of 32 economists surveyed by Bloomberg News.
A pipeline of foreclosures and uneven demand will keep prices from rising this year, discouraging new-home construction and delaying a rebound in housing. Shrinking home equity and an unemployment rate at 9.2 percent are weighing on consumer spending, which accounts for about 70 percent of the economy. "Home prices have yet to find a bottom," said John Herrmann, senior fixed-income strategist at State Street Global Markets LLC in Boston. "Buyers are incredibly cautious. They are concerned about the unemployment rate. There is uncertainty about the economic outlook."
Stock-index futures erased earlier gains after the report. The contract on the Standard & Poor's 500 Index maturing in September was down less than 0.1 percent at 1,333.3 at 9:19 a.m. in New York. Treasury securities were little changed. Estimates ranged from declines of 5.2 percent to 3.5 percent. Year-over-year records began in 2001.
April Revision
The home-price index was revised to show a 4.2 percent drop in the year ended in April from the previously reported 4 percent decrease, according to today's report.
Prices were little changed in May from the prior month after adjusting for seasonal variations, following an April increase of 0.4 percent. Unadjusted prices climbed 1 percent from the prior month, a second consecutive increase.
"The concern is that much of the monthly gains are only seasonal," David Blitzer, chairman of the index committee at S&P, said in a statement. "Sustained increases in home prices over several months and better annual results need to be seen before we can confirm real estate market recovery." The year-over-year gauge provides better indications of trends in prices, the group has said. The panel includes Karl Case and Robert Shiller, the economists who created the index.
The Case-Shiller gauge is based on a three-month average, which means the May data was influenced by transactions in April and March. Nineteen of the 20 cities in the index showed a year-over- year decline, led by a 12 percent plunge in Minneapolis. Washington showed the only increase, up 1.3 percent from May 2010. Eleven cities saw a worsening in their year-over-year price changes.
Housing Headwinds
Other reports signal the housing market is held back by rising unemployment and foreclosures. Sales of previously owned homes declined in June to a seven-month low, according to data from the National Association of Realtors. Inventories rose, more contracts were canceled and 30 percent of transactions last month were of distressed dwellings, the group said.
The Commerce Department may report today that sales of new homes ran at a 320,000 annual pace in June, little changed from 319,000 in May, according to the median forecast of economists surveyed by Bloomberg.
Corroborating Evidence
The Federal Housing Finance Agency reported last week that home prices fell 6.3 percent in May from a year earlier. The FHFA report is based on repeat-sales data that compares prices of the same properties over time. The regulatory agency measures sales of homes with mortgages backed by Fannie Mae and Freddie Mac. As house values decline, owners feel less wealthy and the home equity they can borrow against shrinks.
The lack of a housing rebound is hurting companies that sell related products. Sherwin-Williams Co., the largest U.S. paint retailer, last week reported an unexpected drop in second- quarter profit. The Cleveland-based company cut its full-year profit forecast because of rising raw material costs, and said uncertainty in housing is affecting demand for repainting.
"We're still in a market that is clearly bouncing along the bottom on housing and new construction," Chief Executive Officer Christopher Connor said during a conference call with analysts on July 21. "There is still quite a bit of uncertainty in this market.":
Weak growth may force UK Chancellor into further austerity
by Jeremy Warner - Telegraph
Well there’s a thing. Among the list of excuses for another poor set of GDP growth figures are, bizarrely, Olympic ticket sales. May’s ticket sales, which at around £300m are equivalent to 0.1pc of GDP, apparently don’t count as spending until the event actually takes place in the third quarter of next year. But they would have taken money out of people’s pockets which might otherwise have been spent on other things, so there’s a double negative.
In all, the Office for National Statistics estimates that special factors – which it lists as the additional bank holiday for the royal wedding, the royal wedding itself, the after effects of the Great East Japan earthquake, the first phase of Olympic ticket sales, and record warm weather in April – cost approximately 0.5pc points of growth. If this is added back, then the 0.2pc growth announced on Tuesday for the second quarter doesn’t look so bad.
All the same, it’s quite bad enough, and the truth of the matter is that there are always once off special factors battering the economic statistics. They were not obviously more intense in the last quarter than any other. Why not just put the whole economic crisis down to special factors and be done with it?
The bottom line is that you would expect to see some recovery momentum building by this stage of the cycle, and we are not getting it. Indeed, if anything the outlook is worsening, both domestically and internationally. What can the Chancellor do about it? As I wrote in my column for Tuesday’s print edition of the Daily Telegraph, his options are regrettably limited.
There’s little if any scope for significant tax cuts to support the consumer part of the economy, though as I’ve written before, the Chancellor could reasonably indulge in a number of revenue neutral measures that would boost investment such as reversing the higher 50pc tax band and reintroducing taper relief on capital gains.
But big measures, such as a reversal of the VAT increase, would only knock deficit reduction off course, which in today’s febrile financial conditions would be extraordinarily dangerous.
If there is one thing the Government must do, it is maintain its commitment to fiscal austerity. If the deficit isn’t tackled, interest rates will rise, market confidence would be undermined, and future growth would be severely damaged. Britain and many other advanced economies have no option but wear the hair shirt for a prolonged period of time. Any attempt to wriggle out of this corrective adjustment to the excesses of the boom is the path to ruin.
The one positive in all this is that despite the increasingly weak outlook for growth there’s still every chance of the Government meeting its target of eliminating the structural deficit by the end of the parliament. Perhaps surprisingly, this target is quite insensitive to changes in the growth outlook. Even at rates of growth quite a bit lower than the Office for Budget Responsability has been predicting the target ought to be met.
How to explain this apparent paradox? The Government’s fiscal mandate requires “cyclically adjusted current balance by the end of the rolling five year period” (2015-16), in other words, total public sector receipts need to exceed total public sector spending (minus spending on net investment) after adjusting for the temporary effect of any spare capacity in the economy. The Government has supplemented this mandate with a target for public sector net debt as a percentage of GDP to be falling at a fixed date of 2015/16.
It follows that judgements around how much spare capacity there is in the economy – the output gap – will have a big effect on the cyclically adjusted current budget balance by the end of the parliament. The smaller the output gap, the larger the amount of the deficit that is structural and the less margin the Government has against its fiscal mandate. Conversely, if the output gap is wider, less of the deficit is strucutral and the Government has more margin against its mandate.
Well, the OBR has tested its finding that the government stands a high chance of meeting its fiscal mandate against a persistently weak demand scenario, and finds that lo and behold, the Government would still meet the mandate in such circumstances. It is not entirely clear why this is the case, as logically you would expect weaker growth than expected to act as a significant drag on public finance recovery. The best explanation is probably that unemployment has not risen as much as you might expect for such a deep recession, and that the effect on tax receipts and welfare spending of slow growth will therefore not be as damaging as we’ve seen in the past.
In any case, the OBR reckons that the output gap would have to be 1.5pc of GDP lower than assumed for there to be a significant risk to the fiscal mandate and the plan to eradicate the structural deficit. But what if it is lower, as some economists believe? The longer weak growth persists, the more likely it is that there really isn’t much spare capacity in the economy.
Indeed, the idea that capacity may have been permanently destroyed by the recession may itself be false; it may never have been there in the first place.
If it turns out that virtually all the above trend growth of the boom was the result of credit and leverage, as seems ever more probable, then the output gap is going to be much lower than officially assumed and possibly even non existent.
In those circumstances, the UK economy really is in trouble. If the structural deficit is much larger than the Chancellor currently assumes, he would be forced into additional austerity measures to close it. If he doesn’t take them, the country’s triple A credit rating would be in jeopardy, as its debt dynamics would look correspondingly worse. More troubling still, he’d have to take such action without being able to rely on compensating monetary action from the Bank of England.
To the contrary, the Bank would quite rapidly have to normalise interest rates, whose present highly accommodative disposition is based on the idea that there’s oodles of spare capacity slopping around the economy to soak up any inflationary pressures. Not pretty.
Spanish, Italian Borrowing Costs Soar
by Emese Bartha - Wall Street Journal
Spain and Italy once again paid sharply higher yields than a month ago to sell short-term debt Tuesday, indicating that euro-zone bond markets remain fragile despite last week's agreement on a second bailout for Greece. Treasury-bill auctions in both countries were closely watched for indications of investor demand ahead of bond auctions by Italy on Thursday and Spain next week.
Bonds from both countries came under heavy pressure prior to last week's Greek deal, with yields hitting successive euro-era highs, fueling fears that the countries' funding costs would rise to unsustainable levels. "It's not positive that they had to pay higher yields for the T-bills than previously but even after the Greek deal, the market wasn't very confident," said Alessandro Giansanti, senior rates strategist at ING. "These results indicate that both countries will have to pay jumping yields at their next bond sales."
Spain sold €2.885 billion in three- and six-month T-bills, near the €3 billion maximum targeted. Bids of €9.305 billion imply a healthy bid-to-cover ratio of 3.23 for the amount sold. The three-month average yield rose to 1.899% from 1.568% at the previous auction on June 21, while the six-month average yield increased to 2.519% from 1.776%. Italy sold the targeted €7.5 billion in six-month T-bills and €1.5 billion in zero coupon notes maturing April 2013. The average yield on the T-bills rose to 2.269% from 1.988% June 27. The yield on the zero coupon notes rose to 4.038% from 3.219%.
Italy will auction up to €8.5 billion in two nominal and two floating-rate bonds Thursday. Spain has penciled in the sale of a three-year bond Aug. 4, and may decide to add a second bond. Barclays Capital analysts said these bond sales "are likely to be well supported by redeeming bonds and coupon payments." Given that domestic investors, who have a "very high" propensity to roll over their debt, hold about 50% of the bonds in each country, "there is likely to be a natural demand for the auctions," they said.
Italy's decision to cancel a mid-August bond auction, citing "large cash availability and the limited borrowing requirement" may ease pressure on Italian yields next month. Spanish and Italian bonds fell Tuesday, with Spanish 10-year yields rising above 6%. A trader said the weakness was partly a reaction to the high yields paid at the T-bill auctions, but also reflected worries about how long it would take the euro-zone bailout fund, the European Financial Stability Facility, to be able to intervene in the secondary bond market.
Spain, Italy debt sales show euro zone relief fading
by Paul Day and Valentina Za - Reuters
Spain and Italy paid a high price to sell short-term debt on Tuesday, compounding investors' concern that last week's bailout package for Greece left the euro zone's debt crisis unresolved.
Spain's short-term cost of borrowing hit three-year highs and demand fell at its Treasury bills auction while yields at a sale of six-month Italian paper hit their highest since November 2008.
"The most important point again is the fact that relative to the last auction yields are much, much higher," said Marc Ostwald, a strategist at Monument Securities in London. "It shows we may have had some relief last week, but that relief has proven to be rather short-lived."
Spanish and Italian benchmark bond yields rose after the auctions and the premium demanded to hold Spanish debt rather than lower-risk German bonds widened, reflecting investors' doubts that European policymakers have resolved a crisis that has forced Greece, Ireland, and Portugal to seek international aid.
In another worrying sign, Deutsche Bank's second-quarter results on Tuesday showed that the German flagship lender has been slashing its exposure to peripheral euro zone countries including Spain and Italy. Five days after a euro zone summit agreed a second Greek rescue, Spanish and Italian bond yields are back to the levels seen in the days before the deal was struck. German Bund futures prices, the benchmark of the euro zone debt market, are also back up at pre-summit levels.
Bleaker Reassessment
Last Thursday's agreement aimed to prevent a disorderly default by the debt-laden country and widened the scope of what their rescue fund can do to stop the crisis spreading.
Initial market enthusiasm for the deal saw the euro, peripheral euro zone bond prices, and shares rise.
But the relief rapidly faded as the focus turned to the difficulties in implementing aspects of the package and the fundamental problems of debt sustainability that have yet to be addressed. "The package was viewed quite positively ... Beyond that, it has run into problems over how to implement it. That has been a struggle," Commerzbank rate strategist David Schnautz said.
Top of analysts' concerns is that the euro zone's rescue fund, the European Financial Stability Facility, has not been given extra funds to draw upon despite being handed a much wider remit. "People are concerned that the overall size of the EFSF still hasn't been increased," said Eric Wand, interest rate strategist at Lloyds. "I'd like to think the recent extremes would cap near-term movements but the situation is still very fragile."
There are also question marks about how many banks will sign up to the bond exchanges or buybacks agreed to ease Greece's debt burden. Investment bank JPMorgan said some investors were unlikely to take up the offer to voluntarily swap Greek bonds that were maturing for longer-term paper and would instead sell whatever they had left on their books each time prices rebounded. "We believe that it will be difficult to achieve the required 90 percent participation rate since financial institutions will be tempted to sell Greek bond holdings into recent strength," JPMorgan said.
Procedures for a voluntary swap of privately held Greek government bonds for longer maturity paper will start in August, Greece's deputy finance minister said on Tuesday. Most fundamentally, Greece faces a still mountainous debt to tackle while deep in recession, leading most economist to predict a more fundamental restructuring in future, with all the contagion risks that that prospect entails.
Spain and Italy have been under intense market scrutiny and fears that the crisis could spread to engulf these bigger and systemically more important euro zone states has seen their borrowing costs soar. If either required bailing out the euro zone's resources would be stretched to breaking point.
A week ago, impatience over policymakers' handling of the crisis had driven 18-month Spanish yields to their highest in nearly a decade and the longer-term cost of borrowing was at its highest since the launch of the euro in 1999. Italy's blue chip FTSE MIB has fallen 5.8 percent so far this month, the worst performer among peripheral and major European equity indexes. Spain's IBEX 35 is down 5.3 percent. Italian bonds could come under further pressure as investors make room for sales of up to 10 billion euros worth of longer-term debt on Wednesday and Thursday.
Moody's Cuts Greek Debt Rating Further
by Natasha Brereton-Fukui and Marcus Walker - Wall Street Journal
European bond markets fell on Monday after Moody's Investors Service cut Greece's credit rating three notches deeper into junk territory, warning that the country's latest bailout deal implies a default. Moody's said last Thursday's €109 billion ($156.5 billion) bailout package for Greece will almost certainly inflict "substantial" losses on Greek bondholders, putting the Athens government in at least temporary default.
That assessment echoed the view of Fitch Ratings on Friday, and is expected to be followed by the third major rating agency, Standard & Poor's. The rating agencies are expected to state that Greece is in default on its debt obligations when it begins to exchange its current bonds in coming months for new, long-term debt at a loss to investors. The exchanges are a condition of Greece getting continued rescue loans from the rest of the euro zone, which the country needs to avoid total financial meltdown.
Moody's cut Greece's bond ratings to Ca, its second-lowest rung, from Caa1. A Greek default would be the first by the government of an advanced Western economy in decades. Euro-zone authorities say they hope the default will be orderly and temporary. However, Moody's warned it sets a bad precedent for other cash-strapped euro-zone countries, echoing a widespread perception in financial markets that Ireland and Portugal might also seek sacrifices from their bondholders if they need additional rescue loans from Europe.
Investors have viewed with skepticism euro-zone leaders' insistence last week that Greece is a special case, because Germany, the euro zone's strongest economy and de facto paymaster, has made clear in recent months that it isn't prepared to support further bailouts that are funded only by taxpayers while letting banks off the hook. The precedent set by the planned Greek debt restructuring will weigh on the credit ratings of other euro-zone governments with fiscal problems, Moody's said on Monday. The Greek bond-exchange program is part of an understanding reached among euro-zone authorities and leading European banks and financial institutions last week.
Moody's said it would reassess Greece's financial outlook after the bond exchanges, to judge whether the country is likely to recover or default again. "It's our experience, if you look back at history, that sovereigns that default will often default again," said Sarah Carlson, a senior analyst at Moody's.
However, Moody's said Greece has a chance of repairing its finances after the expected default. "Looking further ahead, the EU program and proposed debt exchanges will increase the likelihood that Greece will be able to stabilize and eventually reduce its overall debt burden," the rating agency said. But Moody's said Greece "will still face medium-term solvency challenges" because of its high debt level, and "will still face very significant implementation risks to fiscal and economic reform."
Greek Prime Minister George Papandreou has expressed a similar view in recent days, saying the European bailout deal leaves the ball in Greece's court, and urging Greek ministers and lawmakers to step up their efforts to overhaul the struggling country's state and economy. On Monday, Greek Finance Minister Evangelos Venizelos was scheduled to meet in Washington with U.S. Treasury Secretary Timothy Geithner, International Monetary Fund chief Christine Lagarde and a raft of fund executive board members to discuss the European financing package, hoping to assure them that his country can carry out the economic programs necessary for an expanded bailout.
Debt-plan concerns hurt Greece’s credit rating
by David Jolly - New York Times
Moody’s Investors Service cut Greece’s credit rating yesterday after concluding the eurozone bailout plan announced last week will require private-sector holders of Greek debt to take credit losses.
The agency said it downgraded Greece’s debt ratings from CAA1, already deep in junk-bond territory, to CA - one step above default - "to reflect the expected loss implied by the proposed debt exchanges." It said it would reassess that rating once the deal has been completed.
Moody’s offered a generally positive assessment of the plan agreed to by European leaders Thursday, saying it "benefits all euro area sovereigns by containing the contagion risk that would likely have followed a disorderly payment default on existing Greek debt."\ But the ratings agency expressed concern about "the negative precedent set by the endorsement of distressed exchanges" between Greece and its creditors, a reference to the bond swaps that private investors will undertake.
Those holding Greek debt are "virtually certain" to suffer losses, Moody’s said. Germany and several other countries had insisted that no new rescue for Greece was possible without banks bearing part of the pain. Fitch Ratings said Friday that doing so would constitute a restricted default.
"While the rating agency believes that the overall package carries a number of benefits for Greece - a slightly reduced debt trajectory, lower debt-servicing costs, as well as reduced reliance on financial markets for years to come - the impact on Greece’s debt burden is limited," Moody’s added.
Standard & Poor’s and Fitch have also rated Greece as junk, or noninvestment grade. The Greek government responded with disdain to the downgrade. "All governments pay a subscription to these agencies," Reuters cited Elias Mosialos, a government spokesman, as telling Radio 9. "We, I think, do not need the reviews anymore. They have no practical value. Perhaps the finance ministry should end its subscription."
Even if the rescue plan manages to hold speculators at bay, Greece remains heavily indebted relative to the size of its economy and needs to expand its gross domestic product.
Greece hopes for quick debt swap in August
by George Georgiopoulos - Reuters
Greece wants a voluntary swap of government bonds for longer maturity paper to start in August and be completed fast to emerge rapidly from an expected default rating, its deputy finance minister said on Tuesday.
Greece's private sector creditors will take a 21 percent loss on their bond holdings as part of a 37 billion euro ($53 billion) contribution to the country's latest bailout plan, agreed at a euro zone summit last week. "In the coming days, in collaboration with (bank lobby) IIF, talks outlining the exact procedure that will be followed so that holders of Greek government bonds choose one of four options and proceed to a debt swap will be completed," Deputy Finance Minister Filippos Sachinidis told Mega TV. "Yes, this procedure will start in August," he said.
The International Institute of Finance (IIF) has estimated a take-up rate of about 90 percent for the voluntary program, which gives banks the option to swap Greek debt with new bonds with maturities of up to 30 years. "If the IIF will be the format that will be finally used, the 90 percent (assumed) participation rate does look optimistic," said Justin Knight, head of European rates strategy at UBS.
Investment bank JPMorgan also questioned whether enough investors would take up the swap offer, and challenged the estimate that investors would take a 21 percent "haircut" under the scheme. It said the loss of capital investment would be more like 34 percent.
Greece's creditors in banking, insurance and fund management are looking for more clarity on the options to swap debt for 15-year or 30-year bonds, paying interest Greece can more easily afford. "It's a complex matter and should be done sooner rather than later. The government is in talks to hire a team of banking and legal advisers," a senior Greek banker who declined to be named told Reuters.
Brief Stay In "SD?"
Credit rating agencies have said they will view the planned bond exchange as a partial default but have left the door open for the overborrowed country to emerge from the rating once the transaction is completed. Fitch has said it will place Greece in "restricted default" during the swap.
On Monday, Moody's warned it will almost certainly slap a default tag on Greece, after downgrading it by three notches to Ca, just one notch above default, to reflect the expected loss implied by the proposed bond swap. The agency plans to review the rating after the swap is done, but unlike Fitch which has pledged to quickly raise Greece to a "low speculative grade," Moody's did not say when the rating would change or how.
With a first working meeting on implementing the plan set to take place in Athens on Thursday, Greek officials hope the bond exchange can be done fast. "The goal is for this (bond swap) to last as briefly as possible," Sachinidis said. "It appears that we will manage to secure a satisfactory participation to proceed with the exchange."
Europe's "Marshall Plan" for Greece may disappoint
by Greg Roumeliotis - Reuters
Europe is promising to help kick-start economic growth in Greece as a way of dragging the country out of its debt crisis, but the scheme looks likely to move too slowly to have much impact in the next couple of years.
At last week's summit announcing a second international bailout of Greece, leaders of the 17-nation euro zone pledged "a comprehensive strategy for growth and investment in Greece" that would "relaunch the Greek economy." The emphasis on growth is an important shift in Europe's approach to the crisis; the first bailout of Athens, launched in May last year, focused instead on slashing the Greek budget deficit, and the reduction in spending hit the economy hard.
Greece's recession was a key reason that it missed targets for cutting its debt under the first bailout. So ending its economic slump quickly would increase its chances of bringing its debt down to manageable levels over the next several years. Details of Europe's plan so far, however, suggest it will be a limited scheme that concentrates on channeling funds for infrastructure development to Greece and has little impact over the next two years, which will be a key period in determining whether Athens forces more losses on private creditors.
"Greece will get the money, but most will reach the economy in 2014 and 2015. Too many projects have yet to be set in motion," said Nikos Diakoulakis, a former Greek development ministry official who advises the government on European Union funds.
Limit Expectations
Greece's economy shrank 4.5 percent last year, worse than the 4.0 percent contraction assumed in the first bailout plan, and the International Monetary Fund now expects it to shrink 3.9 percent this year. The IMF predicts meager growth of 0.6 percent next year but this may be too optimistic; a Reuters poll of private analysts conducted in June forecast expansion of just 0.1 percent in 2012 and 0.7 percent in 2013.
Greece has been trying to boost growth by streamlining regulation, cutting bureaucracy and reforming its labor market, but it may take years before such steps have much impact on the creation of jobs and businesses. So the EU's new growth initiative may be Greece's best hope in the short term.
Last week's summit statement was significant partly for what it omitted, however. The initial draft of the statement spoke of a "Marshall Plan" for Greece, a reference to the big U.S.-backed aid program that helped Western Europe recover after World War Two, but that phrase was left out of the final version, perhaps in order to limit expectations. The new economic plan for Greece focuses on the EU's National Strategic Reference Framework Scheme, which channels grants of money to member countries that need help with economic and social development projects.
Greece has 20.2 billion euros of such funds available to it between 2007 and 2013, and so far has tapped only a little over 5 billion euros. In theory, the remaining funds could add some 2.5 percentage points to annual gross domestic product growth over four years, assuming 3.5 billion euros is disbursed each year and there is then a "multiplier effect" as the money stimulates other economic activity, some analysts estimate.
One obstacle to Greece using the money is a requirement for it to match each disbursement of EU funds with some of its own money. Under a deal announced before the summit, the EU will raise its share of funding for Greek projects from an average 73 percent to 85 percent, and Athens is urging the European Commission to increase that further to 95 percent. But Greece has already lost valuable time in creating a pipeline of projects ready to attract EU investment, and even if the government can prevent corruption from siphoning off some money, bureaucratic obstacles will not disappear overnight.
"Greece has the most bureaucratic system in Europe for absorbing EU funds," said Georgia Zempiliadou, a Greek development ministry official overseeing implementation of projects with EU financing. "There are still delays in granting contracts for public works, there are issues with expropriations, licenses, institutions. We will get the money but it will take time to put the processes in place."
Underlining the problems which aid programs in Greece can face, Norway announced in May that it had suspended payment of a $42 million grant to Greece because Athens had not fulfilled commitments and may have broken rules related to the aid.
Dead Projects
The Greek government says 4,762 development projects, with a total value of 5.5 billion euros, are stuck in the country's bureaucratic machine and has vowed to reappraise them so they can either move forward with EU investment or be ditched.
Most of the funds are assigned to major infrastructure projects worth 11 billion euros in total. These include five road concessions where construction has stopped, because banks have frozen funding in response to delays in areas such as securing land. "It is a difficult situation; many of the small projects have stopped. As for the big road projects, they will not start straight away -- there have to be renegotiations so the banks are secured," said George Peristeris, chief executive of GEK Terna, one of Greece's top construction firms.
The government justifies channeling most EU funds to infrastructure by arguing that 40 percent of the recession is due to a collapse of the construction sector, which lost a fifth of its jobs year-on-year in the first quarter of 2011. Greek construction activity, measured by the number of new building permits, plunged 43.9 percent year-on-year in March, according to the latest official figures. The share of public works in overall construction activity was just 4.3 percent.
Some economists believe, however, that Greece could get more bang for its buck by investing in other sectors with quicker returns. "We buy cement and bricks and build highways on which nobody will drive. Ports and airports are nice but we need tradable goods -- we have left only 3 billion euros to invest in things such as manufacturing and tourism," said Dimitris Mardas, an associate professor of economics at Aristotle University.
The summit statement hinted that the focus of EU spending in Greece might change to some extent, saying the funds would be aimed at "competitiveness and growth, job creation and training."
Last week the European Commission unveiled a task force that will offer technical assistance to Greece in absorbing EU funds, appointing European Bank for Reconstruction and Development Vice President Horst Reichenbach as its head. The summit statement also pledged to "mobilize" institutions such as the European Investment Bank, a multilateral lending institution, to help Greece's economy, but it did not elaborate. The EIB's loans in Greece totaled 3.1 billion euros in 2010, up from 1.6 billion euros the year before.
by DemocracyNow
AMY GOODMAN: Welcome back to Democracy Now!, Professor Hudson. What about these latest revelations?
MICHAEL HUDSON: If you’re talking about the revelations of the Senator, these are the second big story to come out in the last two weeks. The first story, really, was two weeks ago when Sheila Bair finished her five-year term at the Federal Deposit Insurance Corporation. And now that she left, she was able to talk about the arguments that were going on while all of this money was being given away. She opposed it. She said none of this money, not a penny, had to be given away at all. She said the job of the FDIC was to do what it did with Washington Mutual and IndyMac. They could have closed down Citibank, they could have closed down AIG and the others. Depositors insured by the FDIC wouldn’t have lost a penny. She said, “That’s what the FDIC does.”She was overruled by Geithner and by the Treasury Department, and especially by Bernanke, who essentially said, “We have to save the rich first. We have to save the gamblers.” There was plenty of money in all of the banks to cover all of the retail vanilla deposits for businesses and families. What there was not money for was for all the cross-gambles that they had made on derivatives—that is, which way interest rates would go, which way currencies would go. And so, this was really a casino. These were bets. And people like the AIG couldn’t pay. And the question is, how are you going to get the winners in this casino to get money from the losers, who are broke? So these $16 trillion worth of loans were all for junk securities. They weren’t for the solid securities that did back out the deposits. These were all for junk gambles, having nothing to do with the real economy at all.
And the result was that while many of the $16 trillion have been repaid, there has been a residue of $13 trillion added to the government debt since September 2008, when all of this began. All this was created simply on a computer keyboard at the Treasury. So the question is, if they can create a $13 trillion on a computer keyboard, taking over Fannie Mae and Freddie Mac, and the Federal Reserve can simply give this money, why can’t they, over 50 years, pay the trillion dollars for the Medicare and the Social Security? It’s—obviously, it’s a charade.
JUAN GONZALEZ: Well, that was precisely my question. Where did this $13 trillion come from? So this was basically all paper, paper loans.
MICHAEL HUDSON: Well, not even paper. It’s electronic. We’ve sublimated the whole thing. The Federal Reserve can create a deposit, just like a bank does. If you go into a bank, you sign an IOU, and the bank adds money to your account. It’s done on a computer keyboard. That’s what money—how it’s created these days. And the government can do exactly what the bank can do. They can create the money on their own computer keyboards. And that’s—usually, they do that by running a budget deficit. That’s why the economy needs a budget deficit to grow. When the government runs a budget deficit, that puts money into the economy and helps us recover from the recession. That’s pretty obvious.
Under Clinton, we had a budget surplus. And what that meant was, normally, that would have pushed the economy down, but the gap was all provided by banks, commercial banks, on their computer keyboards, at interest. They cleaned up. And that’s a situation that President Obama is trying to restore today. Instead of the government creating free money on its keyboard with a deficit, all of the increase in money used by the American economy will be created by Wall Street at interest. It’s completely unnecessary.
JUAN GONZALEZ: Now, let me ask you about the $3 trillion deal that no one yet knows the specifics of, but we’re already getting the outlines of it leaked little by little. This whole issue of eliminating the tax deduction that millions of Americans use for home mortgage interest, this was supposedly what helped so many people be able to buy homes. With the entire housing industry of the United States in crisis, why would they eliminate mortgage interest deduction, which it seems to me would make—mean fewer houses are bought and sold in the United States?
MICHAEL HUDSON: The banks normally wouldn’t back anything that was going to lead to more foreclosures. But in this case the government has told the banks: “Yes, there are going to be a lot more foreclosures, but we’re going to bail you out, because we’ve insured the mortgages.” Eighty percent of the mortgages in America are now insured by the government, so the banks won’t lose the money. By cutting the deduction, this is going to lead to a huge—a higher bailout by the government to Wall Street on the guarantees that Fannie Mae and the Federal Housing Authority have done.
Now, you said one thing, that making mortgage interest deductible makes homes more affordable. It really doesn’t. What happens is, it enables the banks to make a larger loan against the value of the home, and the buyer now has to pay more interest and take on a larger debt, because they have more free money to pay. Whatever the tax collector relinquishes is available to be paid to the banks as interest. So all this tax deductibility in the first place was an attempt to un-tax real estate, so that home buyers could take out larger mortgages. And 80 percent of banks’ business is making mortgage loans.
AMY GOODMAN: Michael Hudson, let me ask you about the Republican proposal dubbed “cut, cap and balance.” It passed the House earlier this week, and the Senate will vote on the measure today. This is House Speaker John Boehner.
SPEAKER JOHN BOEHNER: Also this week, the House passed our “cut, cap and balance” legislation that represents exactly the kind of “balanced legislation” the President has talked about. It provides him with the debt limit increase that he’s requested. But it gives families and small businesses the real spending cuts and reforms that they’re demanding without any job-crushing tax hikes. What this legislation also shows, that it’s not only important to avoid default, it’s also important that we take a meaningful step toward real deficit reduction. This means, in addition to cutting and capping spending now, there should be real structural reforms to our entitlement programs. And there will be no tax increases.
AMY GOODMAN: Senate Majority Leader Harry Reid described the “cut, cap, balance” bill as one of the worst bills in the history of the country.
SEN. HARRY REID: I think this piece of legislation is about as weak and senseless as anything that has ever come on this Senate floor. And I am not going to waste the Senate’s time, day after day, on this piece of legislation, which I think is an anathema to what our country is all about. So everyone understand, we’re going to have a vote tomorrow. I’m not going to wait ‘til Saturday. We’re going to have a vote tomorrow, and I feel confident that this legislation will be disposed of, one way or the other. The American people should understand that this is a bad piece of legislation, perhaps some of the worst legislation in the history of this country.
AMY GOODMAN: Michael Hudson, your response?
MICHAEL HUDSON: He’s quite right. This is an awful piece of legislation, and it’s too bad that Mr. Obama supports it. But you could see it all coming even before Mr. Obama took office, when he appointed the Deficit Reduction Commission. He appointed opponents of Social Security to the commission: Republican Senator Simpson and Erskine Bowles, who was Clinton’s chief of staff. Obama really believes in trickle-down economics. He believes that Wall Street are job creators, not downsizers and outsourcers and foreclosures. That’s the tragedy of all this.
Now, how—the question is, how can a Democratic president put forth a Republican program? There has to be a crisis. Now in reality there is no crisis at all. In reality, raising the debt ceiling has been done for a hundred years automatically. There is no connection between raising the debt ceiling and arguing over tax policy. Tax policy takes many years to work out. All of a sudden, Mr. Obama is going along with the charade of saying, “Wait a minute, let’s create a crisis.” As his former manager Rahm Emanuel said, a crisis is too important an opportunity to waste. But Wall Street doesn’t like real crises, so there’s an artificial non-crisis that Obama is treating as a crisis so that he can put forth the recommendations of the Deficit Reduction Commission to get rid of Social Security that he has supported all along. That’s the problem. He believes it.
JUAN GONZALEZ: You know, I wanted to ask you specifically about that, because every time you turn on the TV now or you read a mainstream newspaper, there are all these quotations from Moody’s and this rating agency and this expert that August 2nd will be a financial Armageddon for the country. And I’m saying to myself, we’ve already been through a financial Armageddon for the last couple of years, and now they’re suddenly saying that, on this date, if this stuff is not passed, if a deal is not reached, suddenly the entire world financial system will be under severe strain.
MICHAEL HUDSON: Well, you had this kind of debt ceiling come up, I think, maybe 20 times under Bush’s administration. It’s a non-threatening thing. It’s something automatic. It’s technical. It’s sort of like going to the corner and having a notary public certify what you’ve done. It’s a technical thing that has nothing to do with real economy or policy at all. They’re pretending it’s a crisis because they have a plan. And the plan is what Mr. Boehner has put forth. Just like after 9/11, the Pentagon pulled out a plan for Iraq’s oil fields, Wall Street has a plan to really clean up now, to really put the class war back in business and get rid of Medicare, get rid of the programs for the poor, and say, “There’s no money for you. We’ve given it all away in the bailouts.”
AMY GOODMAN: So, Michael Hudson, what could President Obama do?
MICHAEL HUDSON: He could say, “This debt ceiling has nothing to do with policy. You want to argue about the tax policy? Fine, let the Democrats and Republicans do it under non-crisis conditions. But this has nothing to do at all with the debt ceiling. If you want to refuse to increase the debt and plunge the economy into disaster, maybe you’d better talk to your campaign contributors and see what they want. Because I know what they say. Your campaign contributors in the Republican camp are my own campaign contributors: Wall Street. And they don’t like crises.” If he said this, you would find that the charade would pop, just like pricking a balloon.
AMY GOODMAN: Well, what about that? I mean, the very people that are supporting the Tea Party, you know, congressmen activists, are these very same financial institutions that, of course, are demanding a lifting of the debt ceiling.
MICHAEL HUDSON: What they’re pushing for really isn’t a default on the debt. They’re pushing for a crisis to let Mr. Obama rush through the Republican plan. In order for him to do it, the Republicans have to play good cop, bad cop. They have to have the Tea Party move so far to the right, take a so crazy a position, that Mr. Obama seems reasonable by comparison. And of course he is not reasonable. He’s a Wall Street Democrat, which we used to call Republicans.
JUAN GONZALEZ: And in terms of the danger to Social Security and Medicare, how do you see the direction that they are hoping to go into, in terms of the reductions on this deal?
MICHAEL HUDSON: As Mr. Obama’s Deficit Reduction Commission said, we have to get rid of Medicare, we have to get rid of Social Security, put the Social Security funds into the stock market, create a stock market boom, create new business for his—for Wall Street. He believes in trickle-down economics.
JUAN GONZALEZ: And the retirement accounts.
MICHAEL HUDSON: Yes. That’s what he believes in. And this would be a disaster, as people have already seen the last time the market crashed.
AMY GOODMAN: What about unemployment? How does it fit into this picture? We say 9.2, but in fact it is so much higher in so many communities. We’re talking 30 and 50 percent.
MICHAEL HUDSON: That’s right. And it’s getting worse. The interesting thing is when you look at the press reports, the adjective you always see is “unexpected” or “surprising.” What that means is plausible deniability, as if nobody could have foreseen it, while every economist I know says, “Look, we’re in the middle of debt deflation.”
In fact, before he took office, Mr. Obama said he was going to fight to make sure that mortgages—relief was given to mortgage debtors, because if there were foreclosures, there was going to be unemployment. He then did absolutely nothing. He broke his promise. And everything that he warned about has taken place. So it really should not be surprising.
JUAN GONZALEZ: I also wanted to ask you about the connection to—from what’s going on here to what’s going on in Europe, and especially in Greece, the situation there. On Thursday, European leaders agreed to a new $155 billion bailout for Greece. Manuel Barroso, who is the European Commission president, said this:
JOSÉ MANUEL BARROSO: We needed a credible package. We have a credible package. It deals with both the concerns of the markets and of citizens. It responds also to the concerns of all member states of the euro area. It is a package that every government has signed up to. For the first time, the crisis, politics and markets are coming together. Now I expect every one of them to go out and defend and implement, with determination, this package.
JUAN GONZALEZ: The connections, if any, between what’s going on in Greece and Europe and the battle we’re having here?
MICHAEL HUDSON: Well, Greece’s should be viewed as a dress rehearsal for the United States. It’s exactly the same thing. Greece didn’t really get any bailout funds at all. All of the bailout funds were given by European creditor governments to the banks that held the Greek bonds. And Greece was told, “Well, there’s a 50 billion euro loss on your bonds that have gone down. You have to sell off and privatize €50 billion of your land and property in the public domain.” So for every euro that the bankers lose, Greece has to sell off an equivalent amount. The idea is to carve up the government and privatize it, just like Illinois and Chicago and Wisconsin and California are doing. So it’s a dress rehearsal for what’s happening here.
AMY GOODMAN: If you talk about dress rehearsal, there are massive protests—there have been—in the streets of Greece, in Spain, when we were just in Britain, in London. What about here?
MICHAEL HUDSON: You’ve seen the protests in Madison, Wisconsin. And in the Greek Parliament Square, in front of the parliament building, there were signs up to say, “We are Wisconsin.” There was a very clear connection they were making that this is a worldwide struggle. What’s happening across the world is an attempt by the financial sector to really make its move and say this is their opportunity for a power grab. And they’re creating this artificial crisis as an opportunity to carve up the public domain and to give themselves enough money. They’re taking the money and running, because they know that unemployment is going up. The game is over. They know that. And the only question is, how much can they take, how fast?


